A declined payment rarely appears as a line in a revenue report. The customer leaves, the order stays unpaid, and analytics records one more abandoned session. For cross-border traffic, such losses are usually higher than for domestic payments.
Two metrics describe this loss: acceptance rate and success rate. They are often treated as synonyms, although each measures a different stage. The article explains how both are calculated, why payments fail, and which changes raise the figures without adding fraud risk.
The payment acceptance rate is the share of payment attempts approved by the issuer or the payment network. It is calculated as approved authorizations divided by all authorization requests over a fixed period.
The metric reflects how banks see the merchant. Merchant category code, acquirer country, and the completeness of data in the request all affect the decision. A falling rate with stable traffic usually points to routing or data quality rather than to customers.
Success rate covers a longer path: from the moment the customer clicks "Pay" to captured funds. In provider reports the same figure often appears as transaction success rate.
The gap between the two metrics is where losses hide. A payment can be authorized and still fail: 3D Secure times out, capture is never sent, or the customer closes the page during a redirect. Acceptance stays the same. Success drops.
In crypto there is no issuer to decline the transaction. Losses come from an expired invoice, an underpayment, or a wrong network, as described in the article on accepting payments via blockchain.
Both metrics are ratios, so the result depends on what is counted. Three distinctions decide whether two reported figures can be compared:
- Acceptance, authorization, and completion. The first two describe the issuer's decision; completion describes captured funds. A report should state which stage it measures.
- Raw and deduplicated rates. A raw rate counts every attempt, so one customer retrying a card four times gives four failures. A deduplicated rate counts unique payment intents.
- First attempts and retried payments. Retries succeed less often than first attempts. Mixing them hides whether routing works or retries carry the result.
Each cause belongs to a different team: risk, product, engineering, or partnerships. Grouping failures by cause shows who fixes what:
- Issuer declines. The bank rejects the transaction on its own criteria: MCC, unusual amount, foreign acquirer. Generic "do not honor" codes are common here.
- Fraud and authentication blocks. Merchant antifraud rules or a failed 3D Secure check stop the payment. Strict rules reduce chargebacks but also cut legitimate buyers.
- Insufficient funds and expired cards. Typical for subscription billing. A card saved a year ago may have been reissued, and the balance may be low on the billing date.
- Technical and integration errors. Timeouts, incorrect request fields, lost webhooks, gateway downtime. These failures are on the merchant's side and are usually the fastest to fix.
- Cross-border and currency issues. Issuers decline foreign transactions more often, and conversion fees make buyers cancel. In Latin America, with dozens of local systems, the gap is wider.
An overall rate hides local problems: a drop from 88% to 84% may come from one issuer in one country. Four cuts of the data make such causes visible:
- Segment by country, issuer, and currency. Comparing BINs within one country shows whether a single bank declines more. Currency segments show where local pricing is needed.
- Segment by payment method and device. Cards, wallets, and bank transfers fail for different reasons. Mobile checkouts lose payments on 3D Secure redirects.
- Separate new and recurring payments. Recurring charges run without the customer and have their own decline profile. Mixing them with new orders distorts both figures.
- Track decline codes and failure stages. Codes show the issuer's reason. Stage tracking shows where the flow broke: checkout, authentication, authorization, or capture.
How to Improve Payment Acceptance and Success Rates
To improve payment success rates, businesses change infrastructure, checkout, and risk rules together. The tools to increase payment success rate below target different causes:
- Use local acquiring and smart routing. To increase payment success rates, cross-border transactions are routed through a local acquirer. Routing picks the provider with the best approvals per BIN.
- Retry failed payments intelligently. Soft declines such as insufficient funds are retried after a few hours or on payday. Hard declines, such as a stolen card, are not retried.
- Implement network tokens and account updaters. Network tokens stay valid after card reissue, and updaters refresh expired details. Both reduce declines in recurring billing.
- Offer local payment methods. PIX in Brazil, SEPA Instant in Europe, stablecoins such as USDT on TRON where cards work poorly. A second method keeps the buyer.
- Reduce checkout friction. Fewer fields, the page in the buyer's language, a price fixed for the payment window. Each extra redirect is a point of exit.
- Tune fraud rules without increasing risk. Each rule is reviewed on data: how many payments it blocked and how many were legitimate. Risk-based 3D Secure checks only risky orders.
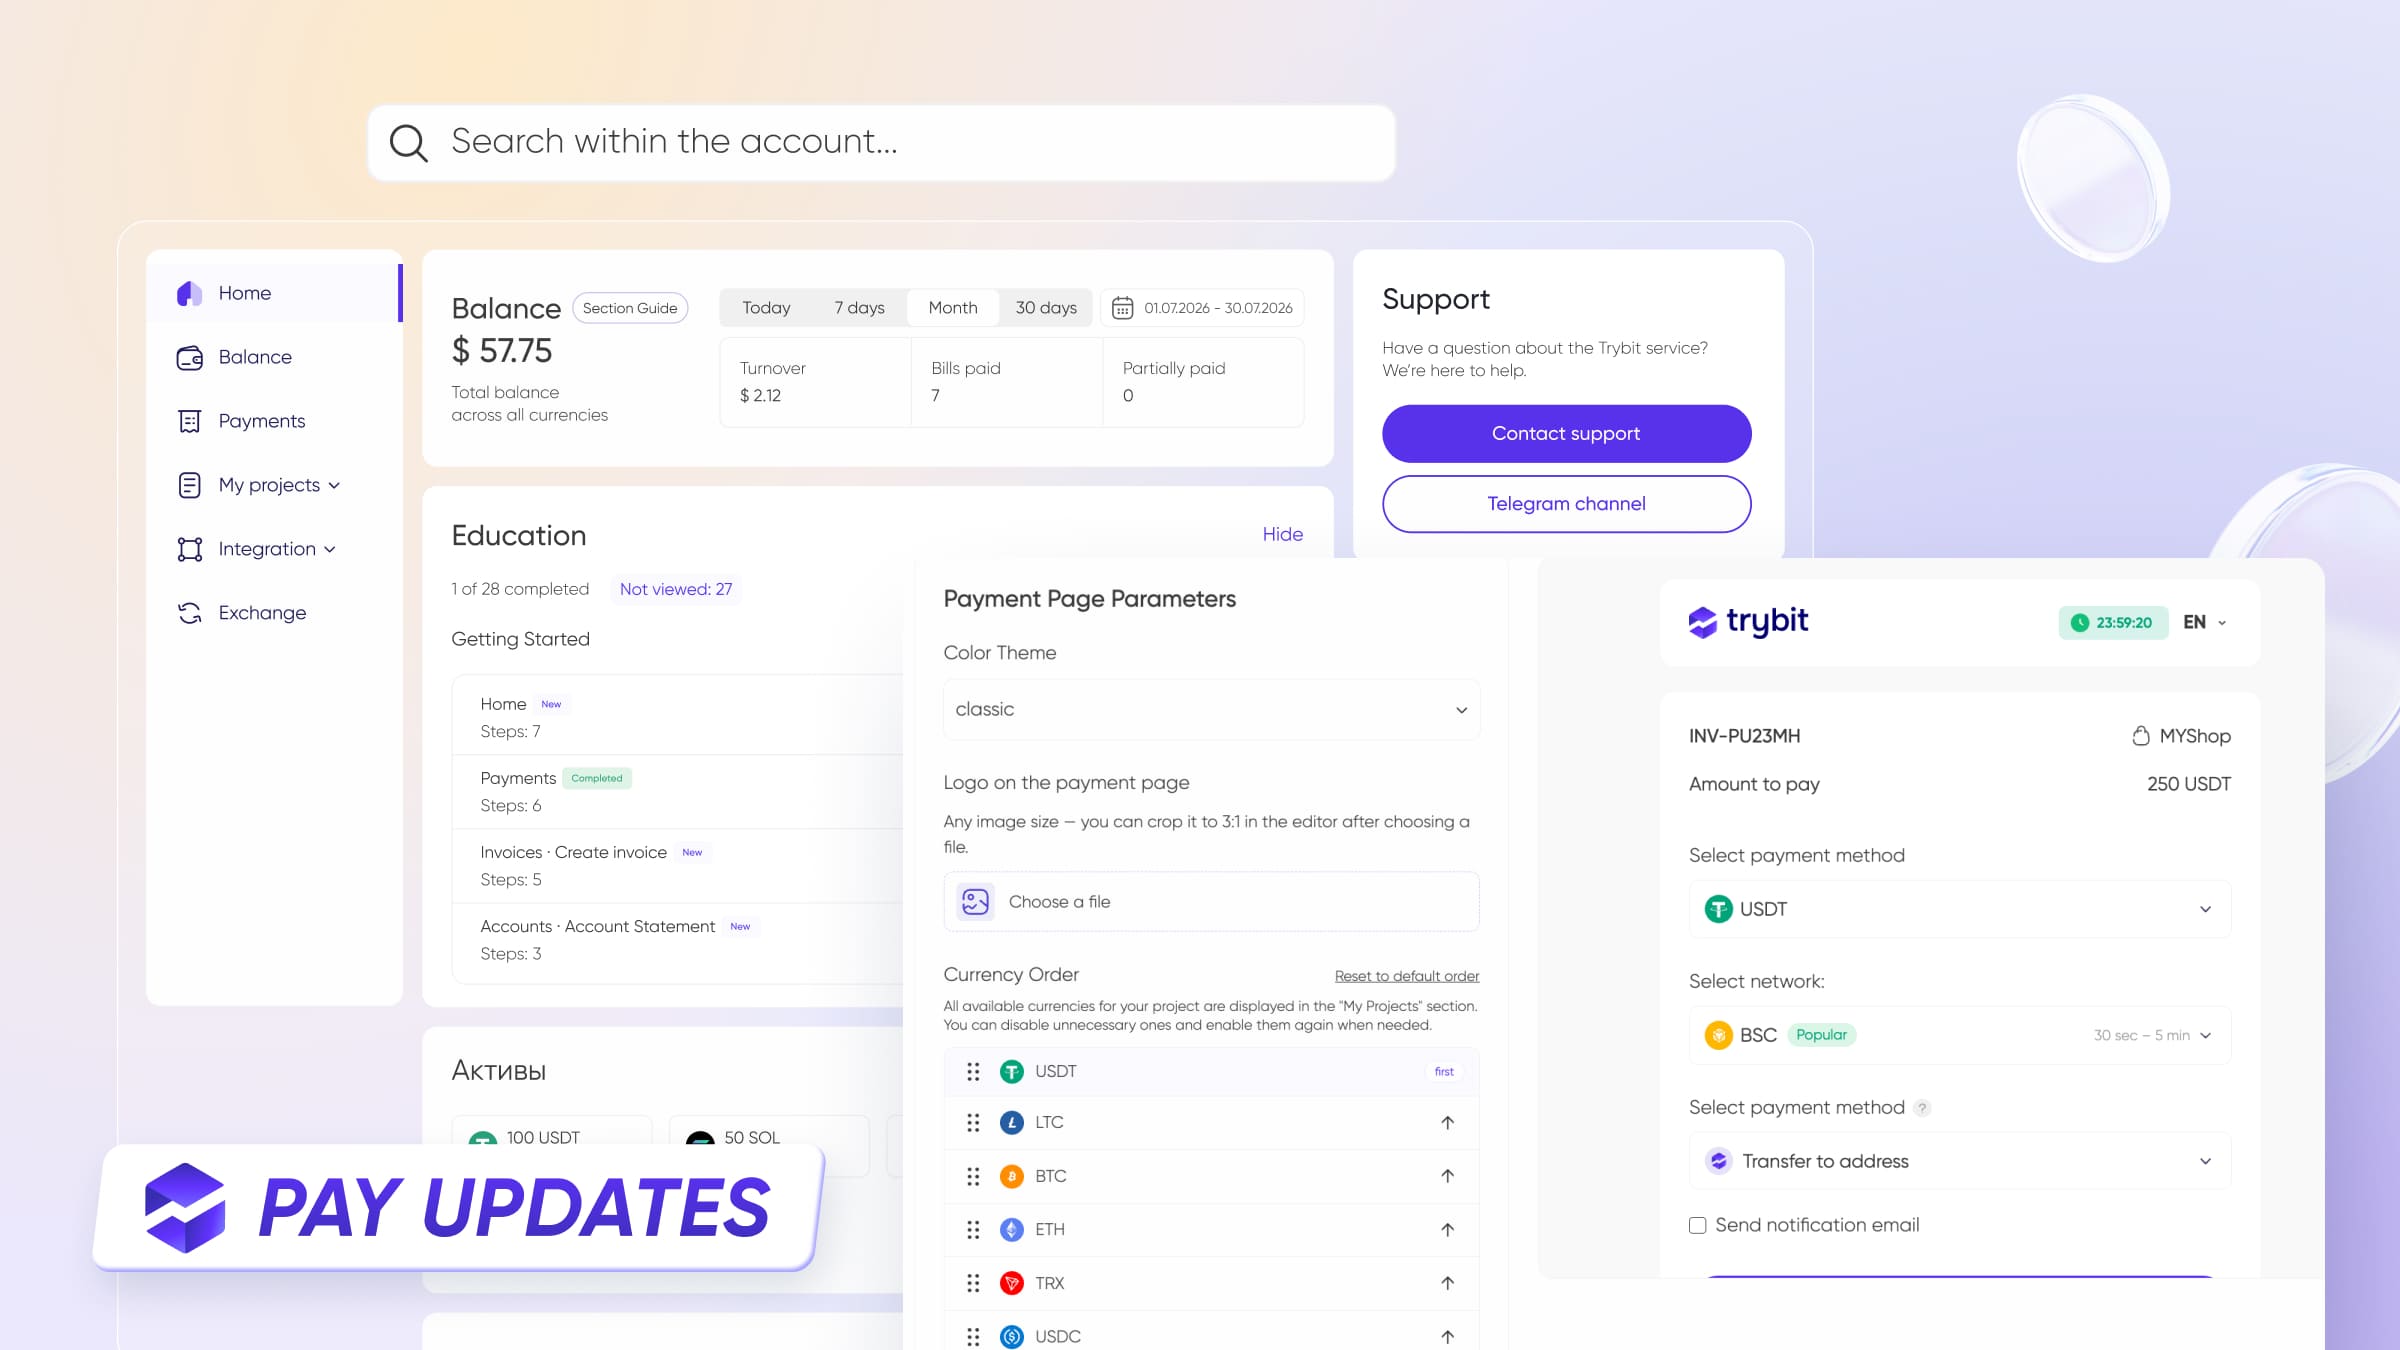
- Accept crypto payments. Crypto does not depend on issuers, so a buyer with a declined card can pay in USDT, Bitcoin, or Ethereum. Trybit fixes the rate for the invoice lifetime and supports Web3 wallets.
No universal benchmark exists: the figure depends on vertical, region, and method. For domestic card-not-present payments in low-risk verticals, acceptance above 90% is common. Cross-border traffic and high-risk MCCs often stay at 70–85%.
The merchant's own history by segment is a more useful reference. If one country or issuer is several points below the rest, work starts there, and the question of how to improve online payment acceptance rates becomes specific: which bank, which method, which decline code.
Teams usually apply the steps below in order, from measurement to new routes:
- Fix metric definitions. Document each formula and whether retries and duplicates are counted. Without this, reports from two providers cannot be compared.
- Segment and map decline codes. Split results by country, issuer, method, and payment type. Group codes into issuer, fraud, funds, and technical causes.
- Remove technical errors first. Timeouts and invalid requests are cheaper to fix than connecting a new partner, and the effect is visible within days.
- Add routes and review rules. Connect a local acquirer or crypto for the weakest segments. Compare recovered revenue with chargeback costs every month.
Acceptance rate shows how often issuers approve requests. Success rate shows how many initiated payments become funds on the account. Tracked together and by segment, they point to the stage where payments are lost.
Most gains come from local routing, reasoned retries, tokens, and a shorter checkout. Crypto adds a route for buyers with declined cards: Trybit supports 40+ currencies and blockchains, with auto conversion to stablecoins. See the guide on how to accept crypto payments on a website and the tips on choosing a cryptocurrency payment gateway.
- What is the difference between acceptance rate and success rate?
Acceptance rate measures approved authorizations. Success rate measures initiated payments that end in captured funds.
- What is a good payment acceptance rate?
For domestic low-risk card payments, above 90%. Cross-border and high-risk traffic often stays at 70–85%.
- Why are cross-border payments declined more often?
Issuers see foreign acquirers as a higher risk, and conversion adds fees. Local acquiring and local methods reduce both effects.
- Should every failed payment be retried?
No. Soft declines such as insufficient funds can be retried later. Hard declines, such as a lost or stolen card, should not be retried.
- How do crypto payments affect the success rate?
Crypto does not depend on issuers, so it gives buyers with declined cards another way to pay.


 8 min