Monday, June 25, 2018

Weekly Indicators for June 18 - 22

May data was focused on housing. Housing starts rose to a new expansion high, but the less volatile and more leading permits made an 8 month low, as did single family permits. As a result of the decline in permits, the Index of Leading Indicators rose less than forecast, at +0.2.

My usual note: I look at the high frequency weekly indicators because while they can be very noisy, they provide a good Now-cast of the economy, and will telegraph the maintenance or change in the economy well before monthly or quarterly data is available.  They are also an excellent way to "mark your beliefs to market."
 
In general I go in order of long leading indicators, then short leading indicators, then coincident indicators.
 
NOTE that I include 12 month highs and lows in the data in parentheses to the right.

Interest rates and credit spreads
  • BAA corporate bond index 4.85% up +.03% w/w (1 yr range: 4.15 - 4.94)  
  • 10 year treasury bonds 2.90% down -.02% w/w  (2.05 - 3.11) 
  • Credit spread 1.95% up +.03% w/w (1.56 - 2.30)
Yield curve, 10 year minus 2 year:
  • 0.34%, down -0.02% w/w (0.34 - 1.30) (new expansion low)
30 year conventional mortgage rate
  • 4.69%, up +0.05% w/w (3.84 -  4.79)
BAA Corporate bonds remain neutral. If these go above 5%, they will become a negative. Mortgage rates and treasury bonds are still both negatives. The spread between corporate bonds and treasuries has now gone above 1.85%, and so I have switched it from positive to neutral. The only remaining positive is the yield curve, and if that declines to +0.25%, that too will become a neutral.

Housing

Mortgage applications  
  • Purchase apps up +4% to 257 w/w 
  • Purchase apps 4 week avg. +3 to 250
  • Purchase apps YoY +3%, 4 week YoY avg. +3%
  • Refi app up +6% w/w
 
Real Estate loans
  • Unchanged w/w  
  • Up +3.8% YoY ( 3.3 - 6.5) (re-benchmarked, adding roughly +0.5% to prior comparisons) 
Refi has been dead for some time. Purchase applications were strong almost all last year, began to falter YoY in late December, but rebounded during spring, ultimately making new expansion highs. The 4 week average declined from the peak enough to qualify as neutral for the last several weeks, but this week rebounded to positive.

With the re-benchmarking of the last year, the growth rate of real estate loans changed from neutral to positive. If the YoY rate falls below +3.25%, I will downgrade back to neutral.

Money supply
M1
  • -1.4% w/w 
  • +1.5% m/m 
  • -0.4% Real M1 last 6 months
  • +3.4% YoY Real M1 (1.6 - 6.9) 
M2
  • +0.1% w/w  
  • +0.7% m/m 
  • +1.4% YoY Real M2 (0.9 - 4.1)
Since 2010, both real M1 and real M2 were resolutely positive.  Both decelerated substantially in 2017. Real M2 growth has fallen below 2.5% and is thus a negative.  Real M1 growth this week was again below 3.5% YoY, and on a 6 month basis it has returned to a negative, so real M1 overall is scored as neutral.

Credit conditions (from the Chicago Fed) 

  • Financial Conditions Index unchanged at -0.81
  • Adjusted Index (removing background economic conditions) unchanged at -0.52
  • Leverage subindex up +.03 to -0.34
The Chicago Fed's Adjusted Index's real break-even point is roughly -0.25.  In the leverage index, a negative number is good, a positive poor. The historical breakeven point has been -0.5 for the unadjusted Index. All three metrics presently show looseness and so are positives for the economy.
 
Trade weighted US$
  • Up +1.31 to 123.92 w/w +1.7% YoY (last week) (broad) (116.42 -128.62) 
  • Down -0.25 to 94.54 w/w, -2.84% YoY (yesterday) (major currencies)  
The US$ appreciated about 20% between mid-2014 and mid-2015.  It went mainly sideways afterward until briefly spiking higher after the US presidential election. Both measures had been positives since last summer, but in the last two weeks the broad measure turned neutral.

Commodity prices
JoC ECRI 
  • Down -3.01 to 109.57 w/w
  • Up +8.23 YoY 
BBG Industrial metals ETF 
  • 133.22 down -3.46 w/w, up +20.14% YoY (108.00 - 149.10)
Commodity prices bottomed near the end of 2015. After briefly turning negative, metals also surged higher after the 2016 presidential election.  With the exception of one week ago, ECRI has been neutral for many months.  On the other hand, industrial metals have been strongly positive and recently made a new high.

Stock prices S&P 500
  • Down -0.9% w/w at 2754.88
Stock prices are a neutral, having not made either a new 3 month high or low in the last three months.  They made a string of new all-time highs beginning in summer 2016.
 
Regional Fed New Orders Indexes
(*indicates report this week) 
  • Empire State up +5.3 to +21.3 
  • *Philly down -22.7 to +17.9 
  • Richmond up +25 to +16
  • Kansas City up +1 to +38
  • Dallas down -0.2 to +27.7
  • Month over month rolling average: down -5 to +24
The regional average has been more volatile than the ISM manufacturing index, but has accurately forecast its month over month direction. After being very positive for most of this year, it has moderated slightly in the last few weeks.

Employment metrics
 Initial jobless claims
  • 218,000 unchanged
  • 4 week average 221,000 down -3,250 
Initial claims have recently made several 40+ year lows and so are very positive. The YoY% change in these metrics had been decelerating but is now back on its multi-year pace. 

  • Unchanged at 97 w/w
  • Up +1.5% YoY
This index was generally neutral from May through December 2016, and then positive with a few exceptions all during 2017. It was negative for over a month at the beginning of this year, but returned to a positive since then.

Tax Withholding 
  • $177.3 B for the last 20 reporting days vs. $181.1 B one year ago, down -$3.8 B or -2.1%
  • 20 day rolling average adjusted for tax cut [+$4 B]: up +$0.2 B or +0.1%
With the exception of the month of August and late November, this was positive for almost all of 2017. It has generally been negative since the effects of the recent tax cuts started in February.

I have discontinued the intramonth metric for the remainder of this year, since the kludge to guesstimate the impact of the recent tax cuts makes it too noisy to be of real use.
I have been adjusting based on Treasury Dept. estimates of a decline of roughly $4 Billion over a 20 day period. Until we have YoY comparisons, we have to take this measure with a big grain of salt.

  • Oil up +$4.85 to $69.18 w/w,  up +61% YoY 
  • Gas prices down -$.03 to $2.88 w/w, up $0.55 YoY 
  • Usage 4 week average up +0.9% YoY 
 The price of gas bottomed over 2 years ago at $1.69.  With the exception of last July, prices generally went sideways with a slight increasing trend in 2017.  Usage turned negative in the first half of 2017, but has almost always been positive since then. Because the YoY change has gone back above 40%, the rating is now negative.

 Bank lending rates
  • 0.452 TED spread down -0.006 w/w 
  • 2.090 LIBOR unchanged w/w (tied for new expansion high)
 Both TED and LIBOR rose in 2016 to the point where both were usually negatives, with lots of fluctuation.  Of importance is that TED was above 0.50 before both the 2001 and 2008 recessions.  The TED spread was generally increasingly positive in 2017, while LIBOR was increasingly negative. This year the TED spread has also turned negative, then turned positive in the past month before returning to negative in the last two weeks.
 
Consumer spending 
  • Johnson Redbook up +4.7% YoY
 Both the Goldman Sachs and Johnson Redbook Indexes generally improved from weak to moderate or strong positives during 2017 and have remained positive this year.

Transport
Railroad transport
  • Carloads up +1.9 YoY
  • Intermodal units up +6.3% YoY
  • Total loads up +4.1% YoY
Shipping transport
  • Harpex unchanged at 678 (440 - 678) (tied for 6 year high)
  • Baltic Dry Index down -27 to 1377 (~700 - 1700)
Rail was generally positive since November 2016 and remained so during all of 2017 with the exception of a period during autumn when it was mixed. After some weakness in January and February this year, rail has returned to positive.
Harpex made multi-year lows in early 2017, then improved, declined again, and then improved  yet again to recent highs. BDI traced a similar trajectory, and made 3 year highs near the end of 2017, declined early this year, but recently has hit multiyear highs.
I am wary of reading too much into price indexes like this, since they are heavily influenced by supply (as in, a huge overbuilding of ships in the last decade) as well as demand.
Steel production 
  • Down -0.7% w/w
  • Down -0.4% YoY
Steel production improved from negative to "less bad" to positive in 2016 and with the exception of early summer, remained generally positive in 2017. It turned negative in January and early February, but with the exception of three weeks (including the last two weeks) has been positive since then. 
 
 
SUMMARY: 

Among the long leading indicators, the more leading Chicago Fed Financial Conditions Indexes and real estate loans remained positive, rejoined this week by purchase mortgage applications. Corporate bonds and mortgage rates are neutral, rejoined this week by real M1. Treasuries, refinance applications, and real M2 are all negative. That the most leading monthly housing data for May declined to seven month lows is also noteworthy.

Among the short leading indicators, industrial metals, the regional Fed new orders indexes, financial leverage, jobless claims, gas usage, and staffing are all positive. Stock prices, gas prices, and the spread between corporate and Treasury bonds are all neutral, rejoined this week by the ECRI commodities index. The US$ is mixed. Oil prices turned negative.

Among the coincident indicators, positives include consumer spending, Harpex, and rail, joined this week by tax withholding. The Baltic Dry Index is neutral. LIBOR and TED remain negative, joined this week by steel.

There were a number of small moves this week across the spectrum, but (except for the unreliable tax withholding) all but one were to the downside.  As a result, while both the nowcast and the short term forecast remain positive, they are a little less so than in the last few months. The longer term forecast crossed the line ever so slightly from positive to neutral several weeks ago, and remains neutral.

Friday, June 22, 2018

Gimme shelter update: housing purchase affordability


 - by New Deal democrat

Let's update one measure of housing prices: comparing of the purchasing power of buyers vs. the price a typical house.  There are at least 3 indexes.

First, here is the N.A.R.'s "Housing affordability index," updated through May. This compares their estimate of median household income vs. the median price of an existing home:


Note that the data isn't seasonally adjusted, so there is an annual cycle. Even so, it is clear that affordability is at its lowest in 10 years. But on the other hand, the index is nowhere near its lows of 2005 or 2006.

Second, the private firm ATTOM Data Solutions publishes an index comparing annualized wages to median house prices:


This, like the N.A.R.'s Index, just made a 10 year high, or low, depending on how you look at the data, but again, is nowhere near the level of u affordability from the peak of the housing bubble.

Finally, here is the comparison, performed by Political Calculations, of monthly median household income, as measured by Rentier Research (which recently restarted this feature), compared with the median price of a *new* home:


New houses, as opposed to existing houses, are at new all time highs, even as compared with the peak of the housing bubble.

The sharp difference in affordability between new and existing houses is probably the main reason why existing houses most recently have sold after an average of only 27 days on the market, and months' inventory of existing houses is at all time lows.

Finally, just keep in mind that this measure does not tell us what the monthly mortgage payment for the median house will be. Because interest rates, even with recent increases, are still 1%-2% lower than they were during the 2000s housing boom, the monthly mortgage payment is nowhere near an extreme at this point.

Thursday, June 21, 2018

The state of the housing cycle


 - by New Deal democrat

The housing market generally proceeds according to an established cyclical rhythm.

My post describing the current status of that cycle as measured by interest rates, sales, prices, and inventory can be found at XE.com.

Wednesday, June 20, 2018

Further comments about the state of the housing market


 - by New Deal democrat

Here are some additional salient comments about the housing market right now.

1. Existing home sales are completely stagnant

Not only did existing home sales fall for the month, not only are they down slightly YoY, but they are now less than 2% higher than where they were 3 years ago:


In May 2015, houses sold at a 5.35 million annualized rate. In today's repot they were reported as selling at a 5.43 million annualized rate.

This, of course, is at complete variance to the very positive trend of new home sales over the last three years.

2. Not only sales, but inventories of new vs. existing houses have completely diverged

There was a great article this morning on housing over at Barry Ritholtz's The Big Picture. Be sure to read it all, but here are a couple of important graphs from the piece.

Inventories of existing houses are continuing to shrink, while inventories of new homes have been slowly rising for the last couple of years:


3, Why the divergence?

The K.I.S.S. explanation is that *prices* of new and existing homes have been moving roughly in lockstep, up about 6% YoY by nearly any measure, for the last 5 years. Pricewise, they have established a stable equilibrium. Thus, the other measures tend to gravitate back to whatever is necessary for that equilibrium  point.

An interesting point that the authors of the article at The Big Picture make is that the price differential between new and existing houses has expanded from 10% to 30% since 2006:


Meanwhile, the size of new houses has increased by 10%. That obviously explains some of the difference, but there is roughly another 20% that isn't so explained.

4. Foreign buyers?

The one possible explanation that isn't covered in The Big Picture piece is whether wealthy foreign (mainly Chinese) buyers are driving up the prices of (the relatively luxurious) new houses. I haven't seen any good articles about this for about three years. At that time it looked like foreign buying might be declining, but maybe it has picked up again since than.

If the profits in new homes are at the luxury end for wealthy foreign buyers with whom in the aggregate domestic buyers can't compete, that would drive domestic buyers to the "substitute goods" of existing homes. But that same dynamic would mean that *owners* (and potential sellers) of existing homes also, relatively speaking, would be unable to afford selling and moving up to the relatively luxurious new homes. Thus existing home inventory would be capped.

Foreign buying is an excellent fit for the missing part of the puzzle. I just don't know if it is factually true.

5. In the aggregate, there's not enough evidence that the housing market is at its peak.

Purchase mortgage applications -- including both new and existing homes -- have been very positive for the last few years. They made a new expansion high about 6 weeks ago. They have backed off since:


(h/t Ed Yardeni's blog)

but they are still running, on average this year, roughly 3% higher than their level of last year.

Yesterday I wrote of a poor report for single family housing permits, While I think the preponderance of evidence is that they are on the cusp of at least trending sideways, I should clarify that there have been several times during the last 5 years when permits have pulled back about 4% from the peak. The difference is that the pullback only lasted 2 months and then permits rebounded. This time the decline has lasted 3 months so far, and while we don't know what the future holds, the fundamentals of interest rates and prices have not improved.

Tuesday, June 19, 2018

Preponderance of evidence from poor housing permits points to slowdown in GDP


 -  by New Deal democrat

The preponderance of evidence, based on this morning's report on housing permits and starts, is that increased interest rates and continuing increased prices are beginning to take a bite out of the market. 

First of all, let's take a look at single family permits -- the most reliable, least volatile of all the measures -- (red, left scale) and total permits (blue, right scale):


Both declined this month, but more importantly, both made 7 month lows. Outside of the expiration of the housing stimulus way back in 2010, this is the first time that single family permits have made this significant a decline -- off about 4% -- during this expansion.

At the same time, since the peaks for single family homes were only in February, and overall in March, not enough time has passed to be confident that this was the peak.

Further, declines of 4% or more took place several times in the 1990s and 2000s without signaling the top of the market, as in 1994-95, 1996, and 2004:


Meanwhile, housing starts made a new high:


This includes on a three month rolling basis, which cuts down on volatility.

But permits lead starts, and in the last eight months there has been an increased backlog of housing permits which have not yet translated into starts. This month that number declined slightly to its lowest since December:


So it is not a surprise that starts have continued to rise even though permits have declined in the last several months.

At the same time, it's worth noting that, even though the economy didn't roll over, in two of the last 3 times -- 1994 and 2004 -- where there was a similar decline in permits outside of recessions, real GDP did slow down:


Should single family permits fail to make a new high for at least one more month, and should the decline be over 5% from peak, I will switch their rating from positive to neutral. And, while the evidence is by no means conclusive, I would say the preponderance of the evidence is that housing is slowing down, and that will have an effect on the economy over the next 6 - 12 months.

Monday, June 18, 2018

Prime age employment participation and wages: not so clear arelationship


 - by New Deal democrat

In the last couple of months variations of the same graph which is supposed  to "solve" the wage conundrum have been going around. I saw another version this weekend:


Easy to see, there is what looks like a nice, nearly linear relationship between the prime age (25-54) employment to population ratio (left scale) with wages as measured by the employment cost index (ECI)(bottom scale).

While I see some merit to the approach, I don't think the graph actually means what its purveyors think it does.

First, let me reproduce it with FRED data, which I am able to do through 2001:


Same pretty linear relationship, with maybe a slight bend at area of 79% participation and 2.5% wage growth.

Now let me do the same thing, except this time, while I am continuing to use the prime age E/P ratio, let me substitute the (inverted) U6 underemployment rate:


Same nice relationship, with a little bit bigger kink at the same point in the graph.

Now let me do the same thing again, this time using the U3 unemployment rate:


Once again, same nice relationship, with more of a kink at that same point in the graph.

In other words, in the source graph that allegedly "solves" the problem, it isn't the employment/population ratio that is doing the heavy lifting at all!  Rather, it is the substitution of the Employment Cost Index for average hourly wages that is responsible for the smoother relationship. That's because, unlike other measures of wages, the ECI has shown increasing wage growth in the last several years:


When we use average hourly wages as the measure instead of the Employment Cost Index, the nice relationship disappears:


And of course, since unlike the Employment Cost Index, average hourly wages go back all the way to the 1960s, we can see what the prime age e/p ratio looks like in previous periods.  Here it is for the 1980s and early 1990s:


Hmmmm, I don't think that is the same nice relationship whereby both increase and decrease together, do you?

When we confine the prime age E/P ratio to just men, to deal with the effect of the secular entry into the workforce by women, here's what we get:


Nope, that is not really helpful proving the case either.

Let me emphasize the I do think there is some merit to the approach. But at least part of the problem is that the labor market can only absorb so many new entrants at any given time, and when too many new entrants saturate the job market (as during the time that tens of millions of women entered the market during the 1970s and 1980s), wages will be depressed.

It is thus probably not a coincidence that the three periods of time during this expansion that have seen the highest rate of new participants in the last 20 years are the exact same periods when wage growth stagnated:


In short, it looks like the nice neat relationship between prime age employment participation and wage growth disappears when we use other measures of wages, and also when we apply it to prior periods.

Sunday, June 17, 2018

Children make the bestest hostages


 - by New Deal democrat

Criticisms of Trump in the business press are especially instructive, because they have no obvious partisan motivation. So Josh Barro's article at Business Insider this morning, castigating his "bully-and-threaten approach to dealmaking," is particularly noteworthy. He writes:
Donald Trump has a negotiating tactic he really likes: Threaten to do something someone else will really hate, and then offer to stop if they give you what you want.  
Call it the "Why are you hitting yourself?" approach to diplomacy. 
(More broadly, I would say that Trump threatens settled norms and agreements in all spheres precisely because others have come to take them for granted, and so have let their guards down.)

After noting that he has imposed tariffs on "national security" grounds even against US allies as a tactic to gain concessions renegotiating on existing trade agreements, they turn to the issue of immigration:
... [H]e has threatened to end the DACA immigration program, then ramped up the separation of asylum-seeking immigrant families, in an effort to press Congress to remake immigration law on his terms, including building a wall. ....
Trump's theory of immigration politics [is that] if he shows a willingness to be more cruel, he thinks that will force Democrats to the table, and that they will essentially bribe him into not mistreating vulnerable people by enacting immigration policies he's long wanted.  
Look at this hostage I've taken, he thinks. How could they possibly let me shoot it?

Like Dreamers and SCHIP recipients, the children of migrants are the most vulnerable, innocent, and helpless of all. Deliberately inflicting suffering upon them will call forth tidal waves of sympathy (witness the White House press conference the other day). So to the amoral and those without consciences, they become the perfect hostages. For that very reason, we should expect that children will be targeted again and again and again throughout the Trump presidency, and that once he has pocketed the ransom, the moment that he the ability to renege on the deal, and take the same hostages all over again, he will do so. Thus, for example, already we hear that funding for SCHIP, which was agreed to for 6 years under the February budget deal, is nevertheless again being zeroed out by the House GOP's proposed budget for next year.

Dealing with such a deliberate tactic calls for cold-blooded calculation, and steely determination. Barro writes:

In government, a combination of pride and political constraints make it very difficult for Trump's counterparties to take the hit and give him what he wants so he will go away. Plus, they know they will have to deal with him in the future and had better not get a reputation for folding easily.

(Chuck Schumer -- who in a panic last February indicated a willingness to vote for funding for Trump's wall, and thereby conceded his leverage on that point --  for your homework write that last sentence on the blackboard 100 times. Not only was poor procedurally, but a completely unsurprising outcome is that Latinos apparently drew the conclusion that Democrats had abandoned the Dreamers after paying lip service to their plight, and are the one minority unenthusiastic about showing up at the polls this November).

Being cold blooded and steely means potentially making the hard decision to protect Dreamers who are already Americans in every way but legal citizenship vs. migrants who are just arriving or may arrive in the future. But above and beyond that, it means using a fine tooth comb to examine, and reject, any deal if there are "trap doors" which would allow Trump of the GOP to renege before the gains to the hostages are realized, or to retroactively undo those gains. Because at the end of the day, appeasing hostage-takers never works.

And alas, for the next 2 years and 7 months, the entire world must deal with and face down the hostage-taker in Chief.

Saturday, June 16, 2018

Weekly Indicators for June 11 - 15 at XE.com


 - by New Deal democrat

My Weekly Indicators post is up at XE.com.

There was a little whipsawing among some data, but the overall picture remains consistent.

Friday, June 15, 2018

May industrial production: meh


 - by New Deal democrat

Industrial production is the ultimate coincident indicator. It is almost invariably the number that determines economic peaks and troughs.

In May it declined -0.1%. While that obviously isn't a positive, it does nothing to suggest any sort of change of trend:


and is in line with any number of similar monthly numbers during the expansion.

In this second graph I've broken it down into manufacturing (blue, left scale) and mining (red, right scale):


Again, there's nothing here to suggest any change of trend. In particular, the energy production sector of the economy which has done so much to undergird the overall number for the last 9 years, continued to improved.

So: meh.

May retail sales come in strong


 - by New Deal democrat

Real retail sales for May came in strong, up +0.6% just in the month:


As the graph shows, this is on trend for the entirety of this expansion, and is also a new high, surpassing that of last winter.

Per capita real retail sales also made a new high, an indicator that the expansion is likely to continue at least one more year:


Finally, the YoY% growth in real retail sales has also been increasing:


Since this is a short leading indicator (3 to 6 months) of the trend in YoY% growth in employment, it suggests that the recent run of strong monthly jobs numbers should continue, averaging in about the 175,000 to 200,000 range over the next few months.

Earlier this week I wrote that real retail sales would show how well the average household is doing holding up, considering the stagnation of real wages over the last several years.  Needless to say, the answer is "fine, so far."

I hope to say much more on this at some point in the next week or two.

Thursday, June 14, 2018

The Fed's actions say "So much for symmetry"


 - by New Deal democrat

Interest rates and money supply are the two long leading indicators under the control of the Fed. With yesterday's indication that they will hike 4 rather than 3 times this year, they are belying their statements that they will treat 2% core inflation as a target rather than a ceiling.

This post is up at XE.com.

Wednesday, June 13, 2018

Chewing over the message of online job postings


 - by New Deal democrat

Here's an interesting graph I came across yesterday. It's from the Conference Board. What it does is track the number of job postings online, and breaks them down between first postings and repeat postings:


Let me say first of all that it is of limited use. The data only goes back to 2005, so there isn't much history -- heck, online job postings didn't even *exist* until the end of the 1990s! Further, online job postings have undergone a secular increase, as more and more companies have come to use it -- so I would expect the historical trend to be positive.  But has it reached maturity? Or is it still in its growing stage?  I dunno .... and probably neither does anybody else.

But with all those cautions, it struck me that the big gap between first time and repeat postings in of a piece with the gap between actual hires and job openings in the JOLTS series:


In the case of online job postings, the repeat postings are either trolling for resumes on an ongoing basis, or else evidence of inability to find a suitable candidate (at the wage the employer wants to pay) the first time around.

What is also interesting is how the two series converged beginning in 2006 as the 2007 recession approached. Which is what I would expect.  As the job situation softens, I would expect companies to pull back on repostings more than original postings, as they become hesitant to go through with a hire if a good candidate does not appear promptly.

I'm not sure what to make of the decline in both during 2016-17. It certainly was not borne out by other employment data.  But for now, the two series continue to diverge. That does not strike me as a sign that companies are skittish about hiring.

Tuesday, June 12, 2018

Gas- and housing-powered inflation mean real wages are going nowhere


 - by New Deal democrat

This morning consumer price inflation for May was reported at +0.2%. YoY inflation was 2.8%. This is tied for the highest in six years (blue):


The cause of the increase was primarily twofold -- and neither one reflective of wage inflation. First, gas prices have increased by over 20% in the past year (red, right scale above).

Second, the costs for shelter (housing) are picking up steam again, up 3.5% YoY(red):


Note that, courtesy of gas prices, inflation for everything else except for shelter has also been rising (blue).

Most everyone assumes the Fed will raise rates again later this week. Let me point out, as others have as well (e.g., Dean Baker) that this will only make housing costs *more* rather than less expensive, and so will not serve to bring inflation down, short of causing a recession.

Meanwhile, while *nominal* wage growth for ordinary workers has finally been rising in the last few months, up 2.8% YoY:


today's 2.8% YoY consumer inflation means that *real* wages haven't grown at all, up less than 0.1% YoY:


Further, since gas prices bottomed in winter 2016, *real* hourly wages have barely risen at all, as shown in the below graph normed to 100 as of February 2016:


Since that time, real wages have increased only 0.3%.

We'll get our best clue as to whether the ordinary American household is simply holding its own, or is in actually undergoing increased stress, when retail sales are reported later this week.

Monday, June 11, 2018

Update: wholesalers' sales and inventories -- it's all good


 - by New Deal democrat

Another slow start to the data this week, so let's take a look at relationship I haven't updated in awhile.

Total sales in the economy are broken up into three categories: manufacturers', wholesalers', and retailers'. We'll get retail sales, the biggest component of the three, later this week. 

But wholesalers' sales and inventories were released last week, and are a useful coincident barometer. They are a better measure than manufacturers' sales, since those have been very much secularly affected by the adoption of just-in-time inventory controls.

The important thing to remember is that sales (blue, left scale) lead inventories (red, right scale).  Here's both for the last 20 years:


Note than in addition to the two last recessions, sales also plateaued first in 2012 slightly before inventory growth did, and again during the "shallow industrial recession" of 2016. As of April, both sales and inventory were both rising, a very typical result during an expansion.

Also, frequently commentators will write about gyrations in the inventory to sales ratio. But a comparison of the ratio (green, right scale) to the more leading measure of sales (blue, left scale) reveals that there the inventory to sales ratio only started to rise significantly coincident (literally, as of the same month) with the downturn in sales for each of the last two recessions as well as the shallow industrial recession of 2016. 


Before that, any such upturn in the ratio was within the range of noise and so gave no meaningful signal. In other words, that inventories might be rising at a faster rate than sales doesn't give us information that is useful in terms of analyzing the business cycle.  And, if anything, the trend in the ratio recently is downward.

So the overall message is that, for now, where sales are concerned, it's all good.


Sent from my iPad

Saturday, June 9, 2018

The disastrous German Emperor who was a doppelganger to Donald Trump: Kaiser Wilhelm


 - by New Deal democrat

You know the drill. It's Sunday, so I write about whatever else is on my mind.

I am presently reading Miranda Carter's "George, Nicholas, and Wilhelm," her 2009 biography of the three grandchildren of Queen Victoria who were respectively, the King of England, Tsar of Russia, and Kaiser of Germany at the time of the outbreak of World War 1.

I was gobsmacked by her portrait of of Kaiser Wilhelm's character, for it is a virtually identical doppelganger to that of Donald Trump.

The best way to show that is via a few excerpts, presented with no embellishment.

First, a look at his "stable genius":

"[Wilhelm] liked to think of himself as another Frederick the Great: politician, soldier, strategist, philosopher, cultural arbiter .... [But s]ome of those who had known him as a prince, however, worried a little about what kind of king he would make.... "He thinks he understands _everything_, even shipbuilding." Bismarck [ ] muttered about Wilhelm's inflated opinion of his own abilities ... and his minuscule attention span: he would "take a little peek ... learn nothing thoroughly and end up believing he knew everything." "

(pp. 75-76)


"Wilhelm considered himself an expert on many things and was not shy about saying so. In later years, he would personally inform the Norwegian composer Edward Grieg that he was conducting Peer Gynt all wrong; tell Richard Strauss that modern composition was "detestable" and he was "one of the worst"; and, against the wishes of its judges, withdraw the Schiller Prize from the Nobel Prize-winning German dramatist Gerhart Hauptmann, whose downbeat Ibsen-esque social realism he didn't like.

"[After, In 1889 in an attempt to smooth over some family difficulties, Queen Victoria had awarded Wilhelm an honorary admiralty of the Royal Navy,] Wilhelm fell upon his new title as if nothing had ever given him so much pleasure in his whole life..... Even Phillip zu Eulenburg noted disappointedly that he was "like a child over it [the British naval uniform]." Wilhelm told Herbert von Bismarck that his British naval title meant that "he would have the right as admiral of the Fleet, to have a say in English naval affairs and to give the Queen his expert advice... [He] was perfectly serious in what he said."
"...[Later that year,] Wilhelm put on his admiral's uniform, flew the pennant of a British navy admiral, and invited himself -- as a real admiral would -- to inspect the British squadron anchored [off the Greek coast].... In December, he sent [Victoria] a plan for the reorganization of the Royal Navy.... In 1891 he sent more "humble suggestions...." "

(pp. 90-93)

On his complete inability to maintain atttention, and wild vacillations:

"Wilhelm appeared unable to distinguish the trivial from the important -- he'd spend hours looking at photographs of warships or moving the position of the smoke stacks on a new cruiser, rather than read government reports.... Worse, he was an appalling vacillator, changing his mind -- he was often influenced by the last person he'd talked to, and constantly in quest of popularity -- with such frequency that it drove his ministers mad and made the government look irresolute and confused. Chancellor Captivi  ... observed wearily that "he often contradicted his official announcements and misunderstandings arose in consequence." His  colleague Marschall, the foreign minister, was more forthright: "It is unendurable. Today one thing and tomorrow the next and after a few days something completely different."

"Then there was his habit of making sudden rogue interventions, getting overexcited during speeches and announcing a new law that completely contradicted agreed government policy, or writing to foreign monarchs without telling the Foreign Office, or appointing someone completely inappropriate to a government position.... He was quick to resent anyone he felt wasn't sufficiently supportive."

(pp. 132-33) 

On his existing in a completely different mental universe:

"...[T]he young kaiser [ ] showed not only an ability to flatly deny something that everyone else knew to be true, but a determination to see the world rather too much the way he wanted it to be...."

On his praeternatural ability to detect personal vulnerabilities:

"[Wilhelm] had an odd ability to home in on people's preoccupations and vulnerabilities.... There were moments when Wilhelm's probings hit a nerve ...."
  
(p. 151)

On his residing in a media bubble:

".... The truth was that, having laid claim to being Germany's savior and the most brilliant man in Europe, Wilhelm had proved quite unable to live up to his promise .... Although he'd told Captivi that the chancellor's job was just a temporary role until he himself was ready to take the reins of government, he had no staying power at all.  "Distractions," Waldersee had observed increasingly bitterly, " ... are everything to him ... He reads very little apart from newspaper cuttings, hardly writes anything himself ... and considers those talks best which are quickly over and done with." Wilhelm was all front. He'd filled his first years as kaiser with a round of pageants, processions, parades and elaborate memorials .... "

(pp.132-33)

Carter's summary is that:

"Wilhelm manifested many symptoms of "narcissistic personality disorder": arrogance, grandiose self-importance, a mammoth sense of entitlement, fantasies about unlimited success and power; a belief in  his own uniqueness and brilliance; a need for endless admiration and reinforcement and a hatred of criticism; proneness to envy; a tendency to regard other people as purely instrumental -- in terms of what they could do for him, along with a dispiriting lack of empathy."

(p. 93) 

That the personalities of Kaiser Wilhelm and Donald Trump are so nearly identical is shocking.

As it turns out, moreover, I'm not the only one who has noticed this identity.
In March of last year, David E. Banks wrote in The Independent the two's similarities. Last October, the magazine Foreign Policy noted that "The Donald Trump - Kaiser Wilhelm Parallels are Getting Scary."  Also last October, the Irish Times published .the following:
One of the foremost historians on the first World War war has compared US President Donald Trump to Kaiser Wilhelm II. 
Professor Margaret MacMillan, the author of the bestselling book The War That Ended Peace, said Mr Trump shares many of the character traits of the Kaiser who led Germany into the first World War.  
She describe those traits as giving the impression of being “reckless, inconsistent  and belligerent”
Trump, rather like Kaiser Wilhelm II of Germany, is vain and has to be the centre of  atte ntion. They both admire the military tremendously. There are a lot of parallels.
 And finally, just this past week, Miranda Carter herself, excerpting some of the same quotes from her book that I have above, wrote in the New Yorker  "What Happens when a Bad-Tempered Distractible Doofus runs an Empire?"

Perhaps the two most depressing takeaways from these comparisons is how Carter notes that other countries found it very easy to manipulate the Kaiser to their own advantage; and Prof. MacMillan's opinion that “He has done something to the US which will take a long time, if ever, to recover from.” 

It would all be just rueful cynicism if Kaiser Wilhelm's bombastic aggressive narcissism hadn't been so pivotal to the miscalculations which exploded into World War.

Weekly Indicators for June 4 - 8 at XE.com


 - by New Deal democrat

My Weekly Indicators post is up at XE.com.

While there were no big changes, the overall theme of slow deceleration continues.

Thursday, June 7, 2018

Gimme credit update: less demand, tightness for consumers


 - by New Deal democrat

I take a more in-depth look at the provision of credit over at XE.com.

While credit is plentiful for producers, the situation looks tighter for consumers.

Wednesday, June 6, 2018

Brief JOLTS update


 - by New Deal democrat

I'm still traveling, so this will be a quick update.

In re yesterday's JOLTS report, the main take seems to be that job openings were higher than the total number of unemployed, so presumably they could all be hired and we'd have actual full employment next month, right?

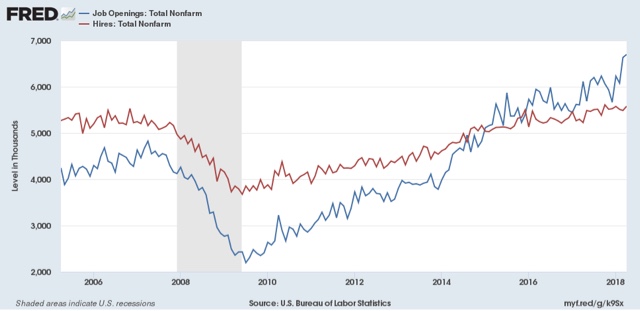
I don't think so. Month after month, hires have totaled considerably fewer than openings for several years. If full employment were so close, why wouldn't hires be catching up?  And every month, there are new layoffs, quits, and other separations, all of whom (except for those who retire) are available to fill those job openings.

In any event, let me focus on the simple metric of "hiring leads firing." Here's the long term relationship since 2000, quarterly through the end of March:


No sign yet of either turning down, although both may be plateauing.

In the 2000s business cycle, hires YoY turned down well in advance of the recession. That isn't the case now:


so there's no danger sign of any oncoming economic downturn in this month's report.

Here is a close-up of the last several years, monthly, of hiring vs. separations:


The YoY comparisons will get more challenging starting next month, as hires have been within a 2% range since last May, and have not made a new high since last October.

Since we are late in the cycle, my anticipation is that we will indeed see negative YoY readings on hiring at some point in the second half of this year, but we'll see.

Tuesday, June 5, 2018

Wage growth: is the dam finally breaking?

 - by New Deal democrat

[Apologies for the light posting: I've been traveling, and there isn't a lot of news this week.]

A couple of months ago I wrote that raising wages may have become a "taboo," i.e., that in some cases employers may be refusing to raising wages, even though it may be costing his money. One of the items I relied upon was from the NFIB, as small business owners presumably are not "monopsonies." As of February, the last time I had data, small business owners were complaining of inability to fill positions, but were not raising wages.

Over the last three months, that may have changed, as revealed in the NIFB survey from May. Let's compare hiring in small business through February:


and now through May:


In the last three months, employment growth per firm has finally broken out to the upside.

Meanwhile, unfilled job openings in small businesses, which have been soaring for the last five quarters (red dots, blue dot at end is for month of May):


are finally giving rise to actual wage increases over the last three months (red dots in the below graph are monthly):


This is supportive of the YoY% growth in average wages for nonsupervisory workers as of last week's employment report for May:


As I noted then, it looks like wage growth for ordinary workers may finally be starting to accelerate.

While it seems crystal clear that the tax cuts for large businesses are just going into stock buybacks, it is certainly possible that small businesses are using some of their extra cash to increase pay for new workers.

If the behavioral paradigm I hypothesized -- that the taboo against raising wages has been undergoing an extinction burst -- the most recent data from the NFIB supports that employers are finally conceding that the Great Recession-era behavior of freezing wages is no longer successful.