Thursday, October 21, 2010

Beige Book: Consumer Spending

From the Beige Book:

Retail spending was flat to moderately positive in most Districts, with the exception of the Richmond and Atlanta Districts, which noted declining traffic and sales. Contacts in the Kansas City District noted sales were stronger than expected; back-to-school spending boosted sales in the Philadelphia and Dallas Districts. Retail spending grew modestly in the Minneapolis and San Francisco Districts, and was flat in the Cleveland, Chicago, and St. Louis Districts. Retailers said consumers are slowly regaining confidence, but remain price-conscious and were largely limiting purchases to necessities and nondiscretionary items. There were reports, however, of a pickup in sales of moderately priced household goods in the Philadelphia, Dallas, and San Francisco Districts, and gains in apparel sales were reported in the Atlanta and Chicago Districts. Inventories were at desired levels. Looking ahead, retailers in several Districts expected modest sales growth through year-end. In particular, some contacts in New York planned to add more holiday staff than last year.

Most Districts reported that sales of new vehicles held steady or rose during the reporting period. Sales of used vehicles were strong as well. Inventories remained tight, particularly for popular vehicles. Used car prices rose, reflective of solid demand and lean inventories. Respondents' outlooks were for slight growth in sales through year-end.

In other words, consumers are generally acting as they should act: they are frugal, looking for bargains and only buying what they need to buy. However, notice that some slightly higher priced luxury goods are entering into consumer purchases. The apparel numbers are confirmed from the retail sales figures, which show a .5% increase from July to August but a .2% decrease from August to September. Also note the inventories are at "desired levels" indicating that inventory restocking for the retail sector is closer to the end than beginning.

Let's take a look at some of the macro data:


Real (inflation-adjusted) retail sales continue to increase.


Notice that online sales decreased until about halfway through the recession and then started to increase. While this area of sales is only 23% of total sales, it is growing in importance.


Real PCEs continue their upward climb


Services account for the largest part of PCEs, coming in at about 66% of PCEs. This part of PCEs was flat for the first part of the recovery, but has since rebounded.


Non-durable goods purchases are near pre-recession levels.

Durable goods purchases -- the smallest part of PCEs, have stalled for the last few months.

Let's take a look at what the individual districts are saying:

Boston: First District retailers report mixed sales results for September and early October. Year-over-year same-store sales range from decreases in the low single digits to increases in the mid single digits. Contacts note that consumers are increasingly responsive to "getting a good deal;" those with increases attribute the uptick in sales to strong marketing, promotional activity, or stocking "the right mix of products" at discounted prices.

NY: General merchandise retailers report that sales have been mixed since the last report, with same store sales running roughly on par with a year ago and on or close to plan in September. Stores in Manhattan fared somewhat better than in the rest of the region, evidently helped by brisk tourism. One major retail chain notes that sales of seasonal apparel were sluggish due to unseasonably mild weather but that sales in most other categories were fairly good; this contact expects holiday season sales to be up roughly 3 percent from 2009 on a same-store basis. Another contact at a major mall in upstate New York indicates a sharp uptick in sales toward the end of September. Some New York State retailers express concern about the recent reinstatement of the state sales tax on clothing under $110, though it is too early to gauge any effect on sales. Inventories are generally reported to be at favorable levels, while prices remain steady; merchandise acquisition costs have also been steady. A few major retail contacts indicate that they plan to hire more holiday-season staff than in 2009. Auto dealers in upstate New York report that sales of new vehicles held up fairly well in August and September, though the cash-for-clunkers program last summer adversely affected year-ago comparisons. Sales and prices of used cars have reportedly been buoyed somewhat by strong demand and lean inventories of new vehicles. Auto dealers report continued improvement in credit conditions.

Philly: Third District retailers reported modest year-over-year gains for the back-to-school shopping period, and most of those contacted for this report said sales have continued to move up in recent weeks. Some store executives noted that customer traffic and discretionary spending appeared to be increasing somewhat. One said, "Sales of home goods have begun to pick up, as well as sales of things that are not necessarily must-have, but the price has to be right. The consumer is incredibly price-sensitive." Looking ahead, most of the retailers contacted for this report said they expect sales to continue to increase at around the current growth rate through the end-of-year shopping period. Most agreed that stronger growth will not set in until economic conditions, particularly employment, show clear evidence of significant improvement.

Third District auto dealers reported steady sales during September at a rate slightly above the year-ago pace. Inventories were generally described as light, and supplies of popular models were said to be particularly lean. Dealers expect sales to improve slowly during the rest of this year and into next year.

Cleveland: On balance, there was little change in retail sales for the period from mid-August through mid-September, when compared to the previous 30-day period. Consumers remain price sensitive and focused on buying necessities. When given the option, they prefer private-label to premium brands. Retailers expect conservative sales growth at best, going through the holiday season. Several retailers noted modest price increases from their suppliers, which they passed through selectively to consumers. Half of our contacts reported on plans to increase capital budgets in 2011 relative to this year. Hiring will be limited to temporary holiday workers.

Auto dealers characterized new vehicle sales during August as decent, although they were slower than those seen during the peak summer season. Many sellers reported that August sales were down compared to year-ago levels due to the cash-for-clunkers program. Looking toward the year's end, dealers expect modest sales increases at best. New car inventories remain on the light side, especially for popular models. Used vehicle purchases have picked up since our last report, although supplies are tight and prices remain high. The number of financing options is growing across the District, and pricing is competitive. Still, credit standards are tight, and potential buyers often find themselves unqualified for the vehicle they want to purchase. The incremental hiring at auto stores that began in mid-summer has tapered off.

Richmond: Retail activity generally softened since our last report, although a few contacts reported an uptick in sales. Several building supply retailers reported declining sales revenues, while a central North Carolina discount department store manager described sales revenues as "steady." A store manager in West Virginia indicated that back-to-school sales were "good, but not shooting off rockets," and a North Carolina department store wholesaler said business had picked up. However, a North Carolina furniture store manager said that local unemployment was causing him to sell at close to cost. Indeed, big-ticket sales, particularly among automobile dealers, fell sharply in our most recent survey. One exception was a car dealer in West Virginia, who reported that sales rose modestly. Recently polled retailers noted flat or declining customer traffic, although a representative of central Virginia merchants reported a modest increase in credit card use. Price growth strengthened somewhat at retail establishments, according to our District survey, while growth in average wages was little changed.

Atlanta: Most District merchants reported that traffic and sales decreased in September and that they are intentionally keeping inventory levels low. Contacts noted that low-end products and apparel were strong sellers, however, and the outlook among retailers improved only modestly from previous reports. District automobile dealers indicated that vehicle sales were ahead of year-ago levels.

Chicago: The pace of consumer spending was little changed from the previous reporting period. Contacts indicated that consumers were slowly regaining confidence, although they remain very price-conscious. As such, promotions and sales persisted as the primary driver of traffic in stores and showrooms. Retail sales excluding autos in September were nearly on par with the August sales pace. Clothing items continued to sell well, as did electronics and appliances; but furniture sales were again weak. Auto sales held steady even as fewer incentives were offered and access to credit continued to slowly improve.

Minneapolis: Consumer spending grew moderately. A major Minneapolis-based retailer reported that same-store sales in September were up about 1 percent compared with a year earlier. September traffic at a North Dakota mall was up over 10 percent from a year ago, which was a surprise following a slight decrease in August, according to the mall manager. Cooler fall weather seemed to attract shoppers. August sales were up over 10 percent at a Montana mall after a few consecutive months of small gains. August sales were up slightly from a year ago at a Minneapolis-St. Paul area mall. A restaurant chain noted that sales were up 3 percent during August and September from a year earlier. However, a Minnesota-based clothing retailer noted slow uptake of new merchandise offerings; it expects low single-digit increases in same-store sales over the next few months. September car sales in Montana were mixed, according to a representative of an auto dealers association.

KC: District retailers reported stronger than expected sales in September and indicated sales were higher relative to last year. Retailers remained optimistic that sales would continue to increase in the coming quarter but expected softness in selling prices. Restaurants reported much higher sales than a year ago and anticipated future sales gains going forward. The average check amount at restaurants remained flat, although menu prices increased. Automobile sales weakened considerably from the last reporting period but remained slightly above year-ago levels. Auto inventories continued to decline and dealers expressed satisfaction with current inventory levels. The lodging industry noted improved hotel occupancy rates with mountain resort bookings above year-ago rates. Some hoteliers indicated that the occupancy bounce was likely seasonal in nature but reported improved expectations for both occupancy and room rates.

Dallas: Back-to-school spending led to a pickup in sales over the reporting period, however customers remain extremely price conscious. Consumers continue to focus on non-discretionary goods, but contacts noted there was an uptick in spending on medium-priced household goods. Eleventh District sales trended roughly in line with the nation during the reporting period. Contacts expressed caution in their outlooks and said competition remains fierce.

Frisco: Retail sales remained sluggish but improved somewhat on balance. Both traditional department stores and discount retail chains reported modest improvements in sales, although somewhat elevated inventories were noted; moderately priced items such as selected home and garden products reportedly saw the strongest gains. By contrast, retailers of major appliances and furniture reported a further slowdown in activity and expressed pessimism for a reversal over the remainder of the calendar year. Grocery sales were characterized as largely flat, with consumers focused on bargains, and grocers do not anticipate any change in customer buying patterns for the foreseeable future. Sales of new domestic and imported automobiles improved a bit, with dealers citing replacement of broken-down or leased vehicles as key motivating factors for purchases.

Here are some overall comments, in no order of importance:

  • Several districts mentioned that consumers were expanding their purchasing to non-necessities, although the increase seems to be cautious.
  • Cleveland, Richmond and Atlanta are a source of weakness for the economy; retail activity in these areas was weak.
  • "Price conscious" was used by several districts, indicating consumers are still wary about making big purchases.
  • Inventories appear to be in line, indicating retail inventory restocking is nearing an end
  • Dallas, KC and Frisco all seemed to be doing OK;
  • Minneapolis showed some incredibly strong numbers.


Beige Book, Part I

The Fed released the Beige Book earlier this week. It essentially says we're in for more of the same -- slow growth.

Reports from the twelve Federal Reserve Districts suggest that, on balance, national economic activity continued to rise, albeit at a modest pace, during the reporting period from September to early October.

Manufacturing activity continued to expand, with production and new orders rising across most Districts. Demand for nonfinancial services was reported to be stable to modestly increasing overall. Consumer spending was steady to up slightly, but consumers remained price-sensitive, and purchases were mostly limited to necessities and nondiscretionary items. New vehicle sales held steady or rose during the reporting period; sales of used automobiles were strong as well. Activity in the travel and tourism sector picked up.

Housing markets remained weak with most Districts reporting sales below year-ago levels. Reports on prices suggested stability, however. Conditions in the commercial real estate sector were subdued, and construction was expected to remain weak. Lending activity was stable in most Districts. Agricultural conditions were generally favorable, and above-average yields were expected in most reporting Districts. Activity in the energy sector continued to expand.

Input costs, most notably for agricultural commodities and industrial metals, rose further. Shipping rates increased, and retailers in some Districts noted rising wholesale prices. However, prices of final goods and services were mostly stable as higher input costs were not passed on to consumers. Wage pressures were minimal.

I'm going to take a look at the data in a sectional way over the next few days.

Yesterday's Markets


Yesterday, stock prices opened higher (a) and rallied for most of the morning (b) using the EMA as technical support. Prices consolidated gains in the afternoon (c), although there was an attempted sell-off at the end of trading on increasing volume.


On the daily chart, prices printed a very strong bar yesterday, and are clearly in a strong uptrend (a). Also notice the EMAs are in the most bullish orientation possible -- the shorter are above the longer and all are moving higher.


The Treasury market opened lower (a), but then moved higher, hitting resistance in the area of previous highs from yesterday (b. Prices sold-off in the afternoon in a disciplined downward move (c).


On the daily chart, notice that Treasuries have broken two uptrends -- the first (a) started about six months ago and the second over the last month (b). However, prices are now moving sideways, largely as a result of QEII from the Fed.


The dollar has hit resistance at the 20 day EMA and moved sharply lower yesterday. This is to be expected, especially with QEII on tap.


Cattle is in an up (A), correction (B) and up (C) pattern with a buy signal from the MACD (D). The USDA's announcement that downgraded this years corn crop is added an upward bid to corn, which is the primary feed for cattle. More expensive food = more expensive cattle.


Copper is still in a very strong uptrend, with two primary trends supporting prices (A and B). However, the MACD has just given a sell signal (C). This bodes well for the economy, as copper is a basic ingredient in most everything.

QEII is a big story driving all the markets right now. It implies more stimulus is on the way, which is bullish for stocks. It places a bid in the Treasury market which is bullish for bonds, but it is bearish for the dollar, which in turn is bullish for commodities.

Wednesday, October 20, 2010

Rockefeller Institute: Sales Tax Receipts up 5.7% in 2nd Quarter

- by New Deal democrat

Back in June I took Mish to task for saying:

Month in and month out we hear the same nonsense about retail sales. I will believe it when I see state sales tax collections support the claims.

I pointed out that state sales tax receipts were,in fact, increasing. Mish still refused to acknowledge the data, citing several states' and municipalities' tax increases (some of them not even sales tax increases).

Well, yesterday the Rockefeller Institute published its final report on state finances during the April - June 2010 quarter, headlined "Sales Tax Gains 5.7 Percent in Second Quarter."

Here's the raw data, from page 17 of the report: Sales tax receipts in the 2nd quarter of 2010 totaled $61.171 Billion, vs. $57.897 Billion in the second quarter of 2009, a gain of $3.3 Billion, or 5.65% (rounded to 5.7%).

Here's a few snippets from the report:

Total state tax revenue in the second quarter of 2010 increased by 2.3 percent relative to a year ago, before adjustments for inflation and legislated changes. The income tax and sales tax both showed growth at 1.6 and 5.7 percent,
respectively, while the corporate income tax declined by 18.3 percent.
...
During the April-June 2010 quarter, enacted tax changes increased state revenue by an estimated net of $4.9 billion compared to the same period in 2009. Personal income tax increases accounted for approximately $2.7 billion and sales tax for approximately $1.6 billion of the change. In a single state, California, legislated changes increased personal income tax and sales tax collections each by an estimated $1.1 billion. Legislated changes in New York were also significant for the personal income tax. Most of the increase in sales tax was due to legislated changes in California, Massachusetts, and North Carolina. [Note: The tables on p. 17 of the report indicate that these three states contributed $1.4 billion of the $1.6 billion increase due to tax rate increases] The net impact is that the increase in nominal tax revenue would instead have been a small decline, if not for the legislated tax changes.
(Italics and note in brackets mine)

Subtact the $1.6 Billion in state sales tax increases from the $3.3 Billion gain, and you have a net $1.7 Billion gain in sales tax receipts ex-tax rate increases, or +2.9%.

As of June 30, 2010, YoY CPI was up 1.1%, meaning that the "real" YoY sales tax increase from the second quarter 2009 was 1.8%.

While this does not exactly mirror the growth in real retail sales, it is noteworthy that, as the Rockefeller Institute puts it:
[E]ven if sales taxes precisely mirrored retail sales, they would be weak compared with two or three years ago. In fact, though, many state sales taxes exempt food and otehr necessities and exempt or exclude many services, relying more heavily on non[necessities. Many of these ... are far easier to do without or postpone.... They tend to ... suffer greater declines in business downturns.

Game. Set. Match. The debate about increasing real sales tax receipts is over.

What's Ahead for Oil?

Oil is an incredibly important commodity. When it's price rises to incredibly high levels it, it usually leads to a recession; in fact, a price spike in oil (the early 1990s and 2008) has preceded two of the last three recessions. Hence, some idea of where it's price is headed can help us understand where the economy might be headed.

First, here is a chart of oil prices:


Prices have stayed in a fairly steady and constant range for most of the year. Now there is a debate emerging about what will happen to oil prices in 2011.

Crude could enjoy its biggest annual increase in demand for three decades. A sustained economic recovery should support oil consumption next year, too, drawing down global oil inventories and forcing Opec, the oil producers’ cartel, to increase production, says Goldman.

It is not the first such forecast. Indeed, talk of $100 a barrel oil was first heard in April, when crude rose as high as $87 a barrel. That was premature but other banks are also forecasting higher prices. Barclays Capital says that risks “are continuing to build towards the upside”.

Yet many dealers in the physical markets, as well as officials at the International Energy Agency, the western countries’ oil watchdog, believe the bulls are wrong. The spot market, they say, is oversupplied and that puts a price ceiling on oil.

“At the risk of appearing a ‘party pooper’ for market bulls, our prognoses still suggest to us that benign market fundamentals could persist well into 2011,” says the IEA.

Mr Taylor argues that the concept of a price ceiling exists today in a way it did not when prices rose to $150 in 2008, before the effects of the financial crisis and the worst recession in decades sapped demand.

His and the IEA’s view is shared, privately, by other leading energy traders. Together, Vitol, Glencore, Trafigura, Mercuria and Gunvor dominate oil trading and, arguably, have better intelligence than anyone else about the state of the physical market. Other banks, including Société Générale, Deutsche Bank and JPMorgan are cautious about the outlook for oil, looking to a ceiling of about $90 a barrel over the next year.

What happens to oil prices will test whether the stability in the market since January – oil has traded at between $70 and $85 a barrel for 95 per cent of the year, in spite of sharp rises in other dollar-denominated commodities – is here to stay. For the four years up to 2008, oil was highly volatile.

Opec, one of the most important actors in the market, believes prices have found a new stability. Saudi Arabia, the cartel’s de facto leader, is working hard to keep oil within the $70-$85 range.

“It is an ideal situation we are in now,” says Ali Naimi, Saudi oil minister. “Nobody is complaining. Consumers are happy, producers are happy. Companies are investing.”

This “steady-as-it-goes” outlook is based on benign fundamentals. The IEA, like many of the big traders in the physical market, is forecasting that oil demand growth will slow next year to 1.2m barrels a day, down from 2.1m b/d in 2010, due to slowing usage in Asia, particularly China, the former Soviet Union and the US.

One of the main reason for the ceiling is prices a large amount of supply in the US:


However, also note the US demand has stalled a bit over the last several years:


However, the real wild card will be China and India; as their economies grow, their demand will be the real driver of prices.


No, Really, This is Not A Good Time For Austerity Measures

Over the last few months, I've been documenting evidence about how universally bad the idea of austerity is. See here, here, and here. There is a time to cut spending, and there is a time not to cut spending. This is a classic example of a really bad time to cut spending:

Austerity measures aimed at bringing down Portugal's towering budget deficit are crucial to regain creditor confidence, Finance Minister Fernando Teixeira dos Santos said Saturday, while also acknowledging that they will slow down economic growth next year.

Measures contained in the government's 2011 budget proposal are intended to "not only reduce the deficit, but will also regain the confidence of those who lend to Portugal," Mr. Teixeira dos Santos said at a news conference explaining the proposal, which the minority government late Friday had presented to parliament amid continued uncertainty on its approval.

The government expects gross domestic product in Portugal to recover by 1.3% this year, but the harsh austerity measures included in the proposal will contribute to a slowdown in GDP growth to 0.2% in 2011, Mr. Teixeira dos Santos said, because the measures will have an effect on domestic demand.

The government's growth forecasts are still slightly above those of the Bank of Portugal, which said last week that it expects a GDP expansion of 1.2% this year, and a stagnation next.

Prime Minister Jose Socrates had earlier proposed a series of harsh austerity measures for this year and next, aimed at cutting Portugal's budget deficit from 9.3% of gross domestic product in 2009, to 7.3% this year, and 4.6% in 2011. The goal is to reduce the spending gap to 2.8% of GDP in 2013.

So, a country that is barely growing is going to cut spending so that it can lower its already low growth rate to near 0%. In other words, the country is voluntarily inching itself toward a recession -- at a time when it is just getting out of a recession. This at a time when there is ample data from other countries that have tried austerity that this is not a good time (see links above) to engage in austerity.

And today, we have another story on the same topic, making the same point:

Britain will take an axe to its welfare state on Wednesday as part of an 80 billion-pound ($125 billion) cut in public spending that will dictate the future of both the economy and the coalition government.

After months of bitter negotiations, Conservative finance minister George Osborne will announce his spending review at 1130 GMT (7:30 a.m. EDT). Cuts of 25 percent on average are in store for most government departments outside priority areas.

Economists are split between those who say the drastic action is needed and those who argue it will tip Britain back into recession. Almost all agree, however, that growth will slow and the Bank of England (BoE) will have to keep monetary policy super-loose for the foreseeable future.


Yesterday's Markets


Equity prices opened lower, but rallied. However, after getting beyond resistance at the 20 minute EMA (b) they hit resistance at just above the 200 EMA (c). Price then fell, eventually hitting support at point (d) at level (e). Prices crashed through this level. They attempted to rally a bit after, (g), but managed no strong gains.


Yesterday, stock prices closed just below key technical levels (a).


In contrast to equities, bonds rallied, forming two upward trends (a and b), consolidating gains along the way in downward sloping pennants (c).


The dollar gapped higher at the open (a) and then moved slightly higher (b).


Yesterday, the dollars spike higher ran into resistance at the 20 minute EMA. Also note the volume spike over the last few days.


The dollar's underlying technicals are strong right now. The A/D line shows a flow of money into the security, the CMF is just turning positive and the MACD is about to give a buy signal. However, given the Fed's QEII policy, this is most likely just a counter-trend rally that will hit resistance at an EMA of Fibonacci level.

Commodities gapped lower at the open, rallied to between the 20 and 50 EMAs (a) and then sold off (b) for the remainder of the day (b).

Tuesday, October 19, 2010

China Market at Key Levels

Earlier today, NDD noted that the Shanghai market was rallying, implying it was a leading indicator. First, I agree with his assessment that the Chinese market is a leading indicator for the US. Secondly, let's take a look at the chart:


On the weekly chart, the market is at important technical and Fibonacci levels.


We can see the recent rally in more detail on the daily chart. The rally is sharp (a) and has recently retreated from important levels (b).

Today China announced it would increase a key interest rate. This is obviously a short-term negative. But over the next few weeks -- given China's growth rate -- I wouldn't be surprised to see this index move through key resistance.

Industrial Production Drops .2%

First, this is an issue I examined over the last few weeks. I looked at manufacturing and concluded the following:
The overall slowdown in durable goods orders indicates the manufacturing sector is slowing. However, the overall ISM readings and numbers from the Midwest should be enough to keep manufacturing from contracting at a strong rate. I think these numbers indicate a level right around 0 is the worst case scenario going forward.
I also noted this:
Manufacturing is clearly slowing. While the overall national numbers are still showing growth, they are just barely positive. The good news here is a cheap dollar should help exports, which -- along with the strong growth in emerging economies -- should prevent this sector from falling into the abyss. But the slowdown across the entire Eastern seaboard indicates this sector is taking a hit from decreased demand somewhere.
Yesterday's drop in IP indicated the slowdown is continuing.
Industrial production decreased 0.2 percent in September after having increased 0.2 percent in August. The indexes both for manufacturing and for manufacturing excluding motor vehicles and parts also moved down 0.2 percent in September. Production at mines moved up 0.7 percent, while the output of utilities fell 1.9 percent. For the third quarter as a whole, total industrial production rose at an annual rate of 4.8 percent after having advanced about 7 percent in both the first and second quarters of this year. The index for manufacturing decelerated sharply in the third quarter: After having jumped at an annual rate of 9.1 percent in the second quarter, factory output gained 3.6 percent in the third quarter. At 93.2 percent of its 2007 average, total industrial production in September was 5.4 percent above its year-earlier level. The capacity utilization rate for total industry edged down to 74.7 percent, a rate 4.2 percentage points above the rate from a year earlier but 5.9 percentage points below its average from 1972 to 2009.
Here is a chart of the data:


Notice the index for IP has been increasing for over a year. In other words, the overall trend is still up. However, as noted above, there are signs of a slowdown.


Above is a chart of capacity utilization, which also shows a strong rebound from the lows of the recession. However, the overall level is still very low and the last month of data produced a sideways move.

Let's break the data down by market groups (from the report):

The output of consumer goods declined 0.4 percent in September.

The index for consumer durables decreased 0.9 percent.

Within durables,

the output of automotive products fell 1.0 percent,

the index for appliances, furniture, and carpeting dropped 1.9 percent after a similarly sized decline in August, and

the production of miscellaneous goods declined for a second consecutive month. The output of home electronics rose 0.6 percent.


The above chart of auto and light truck sales shows that demand has rebounded somewhat, but not as strongly as we would like. It also shows the pace of purchases has been more or less constant for the last approximately six months.

Obviously, the slowdown in the housing market is having a very negative impact on the household furnishings market.

But, overall, production of consumer goods took a hit last month. However, let's look at the data:


Notice the overall trend is still up. In addition, we've seen several 1-2 month drops over the last year and a half without making the overall trend move lower.
The production of nondurable consumer goods moved down 0.2 percent; a fall of 1.9 percent in the energy category, which primarily resulted from a decrease in the index for residential utilities, more than offset an increase in the non-energy category. Within non-energy nondurables, the indexes for foods and tobacco and for clothing moved up, while the indexes for chemical products and for paper products moved down. The output of consumer goods increased faster in the third quarter than in the second quarter, a pickup that reflected unusually strong summer sales by utilities and a jump in the output of consumer automotive products.
The non-durable slowdown was caused by a drop in utility output. This shouldn't be surprising considering the summer is now over. The overall output in consumer goods is interesting, although utilities are a part of that. However, car sales were also a contributor, which is encouraging.

Let's move onto business output.
The output of business equipment edged up 0.1 percent in September and was 10.1 percent above its year-earlier level. The index for transit equipment advanced 1.8 percent and offset a decline in the production of information processing equipment; the output of industrial and other equipment was unchanged. For the third quarter, the output of business equipment rose at an annual rate of 9.8 percent. This increase was slower than in the second quarter due to substantial decelerations in the indexes for information processing equipment and for industrial and other equipment. In contrast, the output of transit equipment jumped at an annual rate of 33.4 percent in the third quarter after having fallen the previous two quarters.
First, note that overall, business equipment printed a strong number, albeit weaker than the previous quarter. In addition, the slowdown was caused by a drop in information processing equipment and industrial and other equipment. Here is a chart of overall business production:


Notice the overall trend is still higher, although the pace of the increase is still lower.


The index for defense and space equipment declined 0.2 percent in September after a 0.5 percent decrease in August.

The production of construction supplies retreated 0.8 percent in September after having advanced 1.1 percent in August. The index for business supplies decreased 0.9 percent in September, with declines in both the energy and non-energy categories.

In September, the production of materials was unchanged from August. A decrease in the output of durable materials offset increases in the indexes for nondurable materials and for energy materials. The decrease in durable materials was its first decline since June 2009, and the indexes for all of its major categories moved down. For the third quarter as a whole, the output of materials rose 4.9 percent, somewhat less than the 7.5 percent advance recorded in the second quarter; relative to the second quarter, slower increases in durable materials more than offset faster gains for nondurable materials and for energy materials.

For a better gauge of construction materials, keep an eye on lumber futures; that's where the first big moves for a housing rebound should occur.

The conclusion from yesterday's report is the same as a few weeks ago: manufacturing is slowing. However, I still think that the worst we'll see is production floating around 0.


Harbingers of the Economic Stall - Updated

- by New Deal democrat

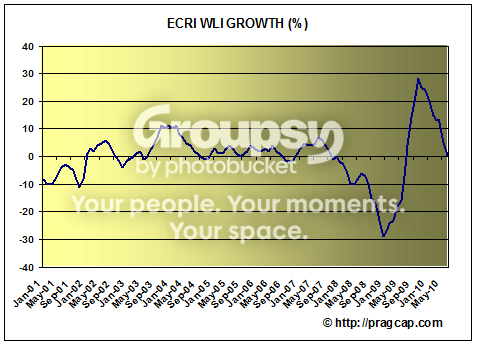
Last week I credited ECRI with its accurate call for a recovery stronger than the last two, through mid-year. At the same time, I have a problem with its Weekly Leading Index (WLI) which it publishes publicly - but then says that others should not rely on. This point was driven home by its collapse between April and July of this year, as shown on this graph:


Through mid-April, it was showing stronger "leading" growth than in any recovery in 30 years. But GDP for the second quarter came in at less than 2%, and the third quarter might even be less. That isn't what I'd call "leading."

Citing that issue, back in early July, noting that virutally all economic data seemed to turn down in unison at the end of April, I highlighted 6 "harbingers of the second half stall:" (1) the Shanghai stock index; (2) Bond yields correlation with stock prices; (3) Price growth exceeded wage growth; (4) Real M1 and M2 money supply stagnant or shrinking; (5) Decline in housing permits and purchase mortgage applications; and (6) Oil prices at 4% of GDP. Since then, it became clear that there was another harbinger, namely (7) rising Libor index. These 7 items all deteriorated before the broad mass of data was hit.

With the LEI, and in particular the stock market, show a few signs of life, I thought it would be helpful to see what those "harbingers" are showing now. Let's take a look:

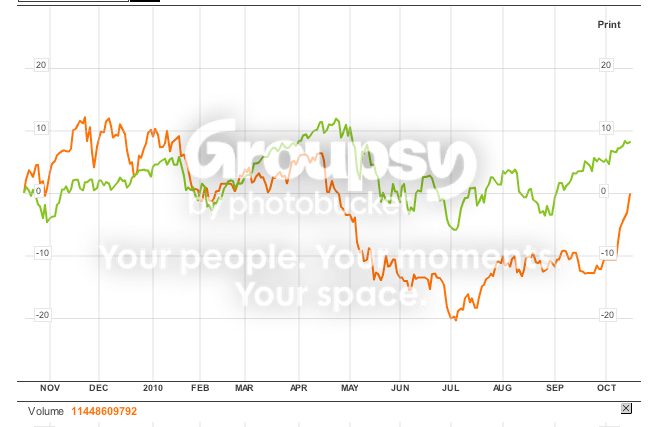
Here is the Shanghai stock index. It has been on a tear since the beginning of July, even more than the US market:


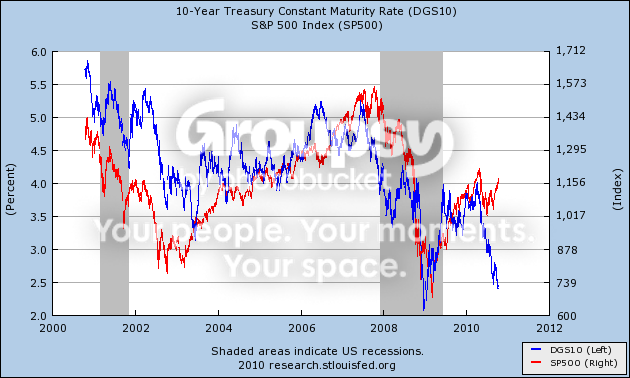
Here is a 10 year graph of stock prices vs. bond yields:


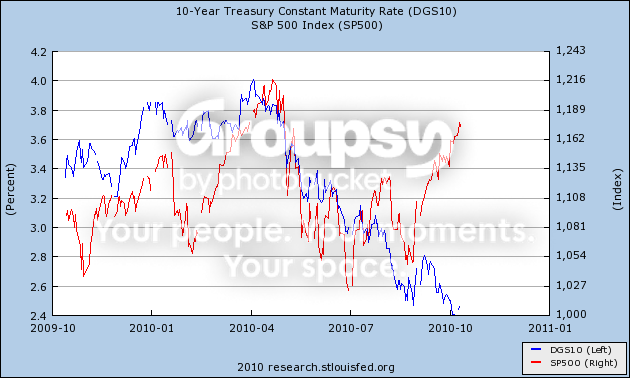
and here is a close-up of the last year. Notice how the two have moved in opposite directions since the beginning of July, vs. in unison since approximately last December (at the time of the Dubai crisis:


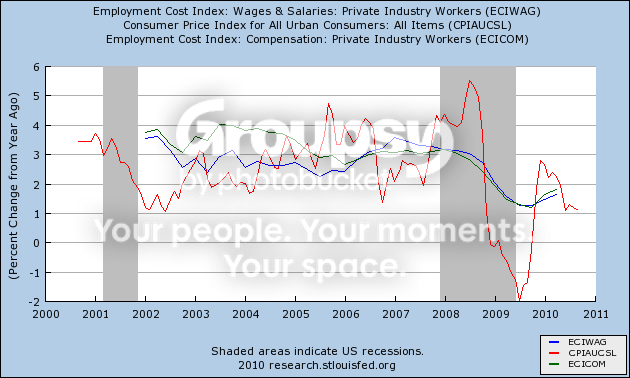
In the last few months, the retreat of any inflationary pressure means that wage gains have almost certainly slightly outpaced prices in the third quarter:


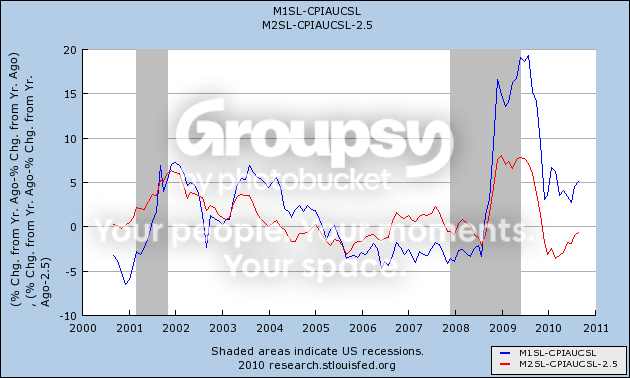
Real M1 and M2 have both turned up. Real M1 was always above the danger zone. Real M2 is getting close:


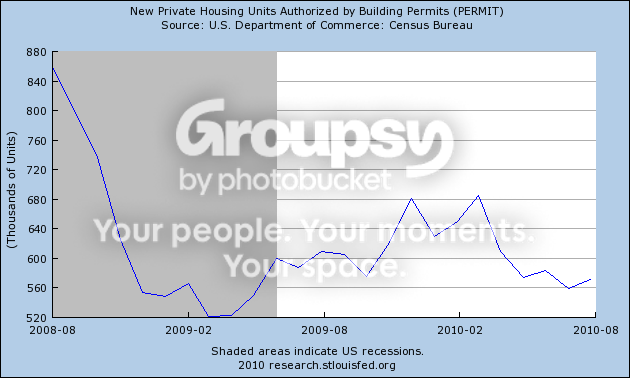
Housing permits have stabilized at a low level:


This morning's data is curious. Permits fell to 538,000, which is close to their 2009 lows. On the other hand, Starts - which typically follow permits closely, sometimes with a one month lag, at 610,000 were among the highest readings in two years. This is quite an anomaly and it will be interesting to see the revisions next month.

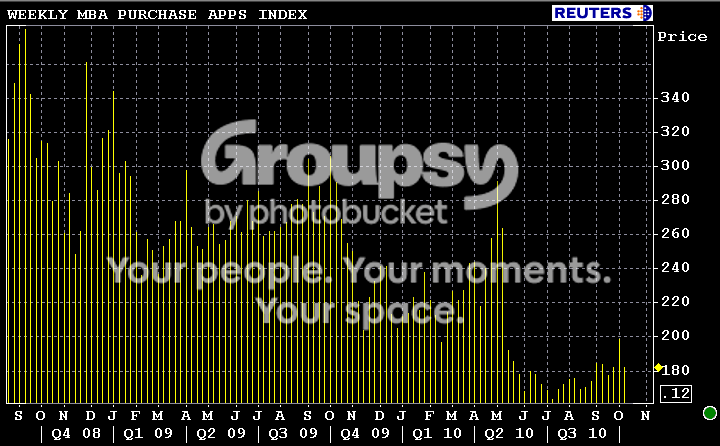
as have purchase mortgage applications:


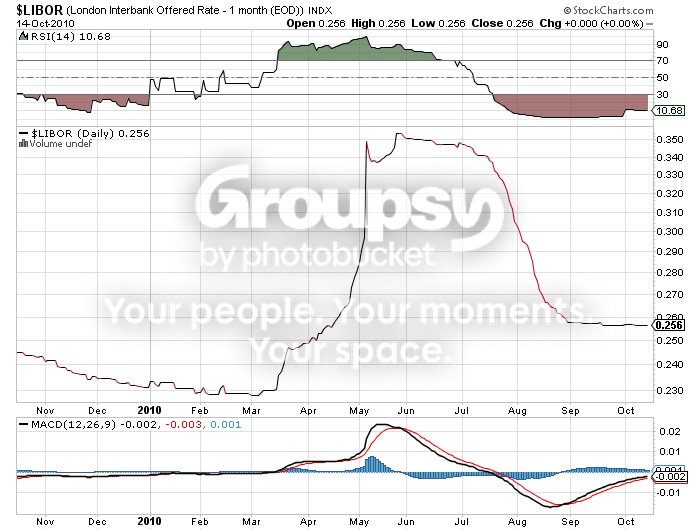
Libor is quiescent. If widening European bond spreads, or foreclosure issues were creating fear of a credit freeze, it would be showing up here. Nothing yet:


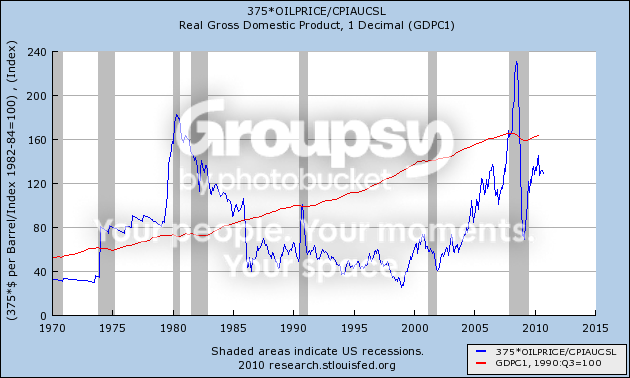
The one item that is of renewed concern is the increase in the price of Oil back over $80 in the last couple of weeks. The below graph is monthly through September:


Note: in the above graph, whenever the blue line has exceeded the red line, that means Oil prices have exceeded 4% of GDP.

In summary, none of our harbingers indicates any further weakening of the economy. In fact, most of them are suggesting short term strength ahead. Yesterday's poor industrial production reading, a classic coincident indicator, is the fruit of the flatlining LEI of this spring, not a foretelling of next spring. Longer term, Oil prices are still a choke collar on economic growth, and "real" wage growth is pathetic at best.


Yesterday's Markets


Equity prices opened higher (a), but lost steam after about an hour of trading (b). Prices moved lower and found support just below the EMAs, where they started to consolidate in a triangle pattern (c). Prices then rallied through two important resistance areas (d) and (e).


Treasury prices gapped higher at the open (a), but fell the EMA's where they rallied but also found support at EMAs in two downward sloping pennant patterns. Also note that prices formed a curving arc for the entire trading session (c).


The dollar had two primary trends yesterday: the first was a confined and well defined downward move (a) followed by sideways consolidation (c).


Commodities had two strong moves higher yesterday (a) and (b). Also note that during the first leg up, prices consolidated in several downward sloping patterns.

Oil is still finding a tremendous amount of resistance around 84. Also note that momentum is decreasing (B) and may give a sell signal soon.

I'm wondering if corn is forming an island reversal (A). However, there is still a tremendous amount of positive data on the chart. The EMAs are all rising (B) with the shorter above the longer and the MACD is also positive (C).

Cotton has also been in the news lately because of its recent price spike (A). Note the momentum is decreasing a big (B), although there is also a very positive EMA picture (C).

Monday, October 18, 2010

What the Fed Sees

From Bernanke's speech on Friday:


The arbiters across the river in Cambridge, the business cycle dating committee of the National Bureau of Economic Research, recently made their determination: An economic recovery began in the United States in July 2009, following a series of forceful actions by central banks and other policymakers around the world that helped stabilize the financial system and restore more-normal functioning to key financial markets. The initial upturn in activity, which was reasonably strong, reflected a number of factors, including efforts by firms to better align their inventories with their sales, expansionary monetary and fiscal policies, improved financial conditions, and a pickup in export growth. However, factors such as fiscal policy and the inventory cycle can provide only a temporary impetus to recovery. Sustained expansion must ultimately be driven by growth in private final demand, including consumer spending, business and residential investment, and net exports. That handoff is currently under way. However, with growth in private final demand having so far proved relatively modest, overall economic growth has been proceeding at a pace that is less vigorous than we would like.

In particular, consumer spending has been inhibited by the painfully slow recovery in the labor market, which has restrained growth in wage income and has raised uncertainty about job security and employment prospects. Since June, private-sector employers have added, on net, an average of only about 85,000 workers per month--not enough to bring the unemployment rate down significantly.

Consumer spending in the quarters ahead will depend importantly on the pace of job creation but also on households' ability to repair their financial positions. Some progress is being made on this front. Saving rates are up noticeably from pre-crisis levels, and household assets have risen, on net, over recent quarters, while debt and debt service payments have declined markedly relative to income.1 Together with expected further easing in credit terms and conditions offered by lenders, stronger balance sheets should eventually provide households the confidence and the wherewithal to increase their pace of spending. That said, progress has been and is likely to be uneven, as the process of balance sheet repair remains impeded to some extent by elevated unemployment, lower home values, and limited ability to refinance existing mortgages.

Household finances and attitudes also have an important influence on the housing market, which has remained depressed, notwithstanding reduced house prices and record-low mortgage rates. The overhang of foreclosed properties and vacant homes remains a significant drag on house prices and residential investment.

In the business sector, indicators such as new orders and business sentiment suggest that growth in spending on equipment and software has slowed relative to its rapid pace earlier this year. Investment in nonresidential structures continues to contract, reflecting stringent financing conditions and high vacancy rates for commercial real estate. The availability of credit to finance investment and expand business operations remains quite uneven: Generally speaking, large firms in good financial condition can obtain credit in capital markets easily and on favorable terms. Larger firms also hold considerable amounts of cash on their balance sheets. By contrast, surveys and anecdotes indicate that bank-dependent smaller firms continue to face significantly greater problems in obtaining credit, reflecting in part weaker balance sheets and income prospects that limit their ability to qualify for loans as well as tight lending standards and terms on the part of banks. The Federal Reserve and other banking regulators have been making significant efforts to improve the credit environment for small businesses, and we have seen some positive signs. In particular, banks are no longer tightening lending standards and terms and are reportedly becoming more proactive in seeking out creditworthy borrowers.

Although the pace of recovery has slowed in recent months and is likely to continue to be fairly modest in the near term, the preconditions for a pickup in growth next year remain in place. Stronger household finances, a further easing of credit conditions, and pent-up demand for consumer durable goods should all contribute to a somewhat faster pace of household spending. Similarly, business investment in equipment and software should grow at a reasonably rapid pace next year, driven by rising sales, an ongoing need to replace obsolete or worn-out equipment, strong corporate balance sheets, and low financing costs. In the public sector, the tax receipts of state and local governments have started to recover, which should allow their spending to stabilize gradually. The contribution of federal fiscal stimulus to overall growth is expected to decline steadily over coming quarters but not so quickly as to derail the recovery. Continued solid expansion among the economies of our trading partners should also help to support foreign sales and growth in the United States.

Although output growth should be somewhat stronger in 2011 than it has been recently, growth next year seems unlikely to be much above its longer-term trend. If so, then net job creation may not exceed by much the increase in the size of the labor force, implying that the unemployment rate will decline only slowly. That prospect is of central concern to economic policymakers, because high rates of unemployment--especially longer-term unemployment--impose a very heavy burden on the unemployed and their families. More broadly, prolonged high unemployment would pose a risk to consumer spending and hence to the sustainability of the recovery.

First, Bernanke -- along with practically everybody else (us included)-- sees a slow growth economy. This really isn't news; this has been the case for the last few months, as the markets and economy have calmed down from the EU/Greece situation in the late Spring. Notice the both 1 month and 3 month libor are now back near pre-crisis levels.

Secondly, the lack of major news is in fact good news. Since the EU crisis, we've seen the markets calm down and appear to settle into an expectation of below to average trend growth. (I should add, I don't think the current mortgage gate will sink the economy -- which I will explain in another post.)

Third, notice that Bernanke notes that things are lining up for future growth. Monetary policy is expansionary but more importantly, the consumer is retrenching and doing so effectively. Savings are up, consumers are paying down debt as evidenced by the drop in the financial obligation ratio. In addition, consumer are also still buying things: PCEs have increased at between 1.5% and 2% for the last four quarters. But the reports from the Beige Book indicate that consumers are more cautious with their purchases and are extremely price sensitive. In other words, they're the kind of consumers they should have been all along.

Last week, I highlighted that if we start to get good jobs numbers for a long-enough period to boost consumer confidence (say, 4-5 months?) we may have the ingredients for a turnaround in housing. I did this to highlight that we're seeing basic events lines up in a way that would lead to more growth. But, largely because of the employment situation, we're in an economic holding pattern.


Do We Need More Inflation?

From Bernanke's speech:

The topic of this conference--the formulation and conduct of monetary policy in a low-inflation environment--is timely indeed. From the late 1960s until a decade or so ago, bringing inflation under control was viewed as the greatest challenge facing central banks around the world. Through the application of improved policy frameworks, involving both greater transparency and increased independence from short-term political influences, as well as through continued focus and persistence, central banks have largely achieved that goal. In turn, the progress against inflation increased the stability and predictability of the economic environment and thus contributed significantly to improvements in economic performance, not least in many emerging market nations that in previous eras had suffered bouts of very high inflation. Moreover, success greatly enhanced the credibility of central banks' commitment to price stability, and that credibility further supported stability and confidence. Retaining that credibility is of utmost importance.

Although the attainment of price stability after a period of higher inflation was a landmark achievement, monetary policymaking in an era of low inflation has not proved to be entirely straightforward. In the 1980s and 1990s, few ever questioned the desired direction for inflation; lower was always better. During those years, the key questions related to tactics: How quickly should inflation be reduced? Should the central bank be proactive or "opportunistic" in reducing inflation? As average inflation levels declined, however, the issues became more complex. The statement of the Federal Open Market Committee (FOMC) following its May 2003 meeting was something of a watershed, in that it noted that, in the Committee's view, further disinflation would be "unwelcome." In other words, the risks to price stability had become two-sided: With inflation close to levels consistent with price stability, central banks, for the first time in many decades, had to take seriously the possibility that inflation can be too low as well as too high.

A second complication for policymaking created by low inflation arises from the fact that low inflation generally implies low nominal interest rates, which increase the potential relevance for policymaking of the zero lower bound on interest rates. Because the short-term policy interest rate cannot be reduced below zero, the Federal Reserve and central banks in other countries have employed nonstandard policies and approaches that do not rely on reductions in the short-term interest rate. We are still learning about the efficacy and appropriate management of these alternative tools.

The preceding paragraphs were the first three of Bernanke's speech on Friday and they have been on my mind for the last few days. Let me explain why.

First, here is a chart of the year over year percentage change in inflation:


There are two periods. The first is 1960-the early 1980s, which are characterized by higher and higher inflation. This ended after Paul Volcker's tenure at the Fed. From 1980 onward, inflation has been relatively subdued. It has increased before all the major recessions, but the highest year over year total we've seen is a little over 5% -- hardly a problem.

As Bernanke notes, low inflation implies low interest rates. Here is a chart of the 10 year CMT Treasury for the last 40+ years:


Notice that as inflation has come under more and more control, interest rates have come down.

Let's think about this from a policy perspective. The big problem with low inflation is low interest rates, which in turn can lead to speculative bubbles. As money gets cheaper and cheaper (as its cost drops) it becomes more and more likely that people will borrow money. In other words, a central cause of the financial bubbles we've been seeing over the last 20 years is low interest rates -- and the Feds continual lowering of rates to stimulate the economy. But this was caused by the Fed being successful in limiting inflationary forces in the economy.

I realize this is a chicken or the egg type of circular flow, but it's very important to understand exactly what has been going on for the last 30 years. Because inflation is less of an issue, the Fed has been able to lower short-term interest rates. This in turn has created several speculative bubbles.

In other words, it's distinctly possible the economy needs more inflation than we currently have.


Objective Facts; They're For Real

Just added over the weekend below the blog head is a quote from Jon Stewart: Objective Facts; They're for Real. This a proposed sign from his Rally to Restore Sanity webpage (which I'm going to, BTW). Let me explain why I love this quote and why it is central to this blog.

Several weeks ago, a commenter left us the following, well, comment:

In the time I've read this blog, I've found the accuracy of their predictions are entirely due to an almost scientifically objective analysis of data, not from luck. They can't predict everything, but when they can't, they just say so.

I originally started writing about economics on a political blog, Daily Kos. And while I am grateful for the opportunity to develop my writing skills there, I was also constricted by the blogs political bent. Analysis had to conform to a particular world view. When analysis didn't conform to a view, it was attacked as "written for the man" or "propagated by a corporate shill" -- you get the picture.

I started this blog in the winter of 2006 and did so largely to write more about economics and less if at all about politics. Over the course of the last four years, I have been more and more about data -- what do the facts tell us about the economy. Not, "what do I really wish the facts said."

As I have asked people to add their writing to the blog (New Deal Democrat, Silver Oz, Brodero) I have asked them for one thing: stick to the data and what the data tells you. That's basically all I require from my contributors. And that is pretty much what we have done for the last few years here at the Bonddad Blog.

If you want hyperbolic rhetoric or ranting, go somewhere else. There are plenty of other sites that cater to that type of audience.
If you think the world is coming to an end, believe me -- there are plenty of other writers who will confirm your view. When you get here, realize you will get a lot of data and interpretation thereof. Also realize we will continue to look at the same data over a period of time to get an idea for what the trends are. That's what we like and that's what we'll stick to. The more data and facts, the better off we'll be.


Yesterday's Markets


On Friday, the markets opened higher (a), sold off in a hurry (b) and then consolidated their gains in sideways action for the rest of the day, with price action that gravitated between (c), (d) and (e).


Notice the Bollinger band pattern -- the wide bands at the open (a) and the narrow bands at the end of the day (b). Bollinger bands measure volatility; as volatility drops the bands narrow. This is why the bands narrow when the markets are consolidating.


The 7-10 year part of the curve has been declining for the last two days, with counter-trend rallies (a) that use the EMAs for resistance.

For more on the technical outlook on the bond market, see this post from Corey over at Afraid to Trade. However, remember the Fed has announced a QEII program which will add a strong bid to the bond market for however longer that program is in effect.


The dollar rose a bit on Friday (a), with some consolidation along the way in the form of downward sloping bull market flags/pennants (b).


However, this was a counter-trend move; the dollar is still in a clear downtrend, which is adding a bid to the commodities market.


Commodities have also been selling off for the last two trading days, although there have been some counter-trend rallies as well (a).