Wednesday, December 5, 2007

Today's Markets

Wow -- the incredibly wild ride continues.

SPY: +1.7
QQQQ: +1.78
IWM: +1.85

The markets gapped higher at the open. Then they bounced around until they all finally closed on a strong upward surge on heavy volume in the final five minutes of trading. But below, notice all of the gaps on the charts -- again. The volatility is really high right now. Prices are really jumping around.


Below are the 10 day charts for the SPYs, QQQQs and IWMs respectively. Notice how all of the charts are jumping around; there is no clean direction either up or down. Instead, we're seeing a ton of really wild moves in both directions.


There is nothing clean about this market; there is no trend in any direction. Instead, it's like an anxious schizophrenic throwing paint at a canvas.

In fact, the market action is making me feel sick -- I mean really sick

Can the Treasury Market Rally Continue?

Here is a chart of the 7-10 year Treasury ETF.


The Treasury market has been in a strong rally since early July. The primary reason for this rally is concern in the credit markets. Because Treasuries are considered the safest investments around, investors will flock to them when they are concerned about something in the economy. The credit crunch has obviously spooked investors, sending them flocking to Treasuries for the last 5 months.

But how long can this rally continue? Unlike stocks which theoretically have unlimited upside potential, bonds are constrained by their interest rates. Here is 40 year chart of the interest rate on the 10-year constantly maturing treasury.


The chart is pretty clear. We're at historically low interest rates on the 10-year Treasury.

Here is a 5-year chart to better see recent movements.


I've circled the areas where the prevailing interest rate was at or below current levels. Notice we had an extended rally in early 2003 that drove rates to levels below the present level. We also had a brief rally in early 2004 that pushed levels to current levels. But referring to the above 40-year chart those are the only times in the last 40 years rates have been this low.

In the financial markets, anything is possible. And considering the current concern about the credit markets, it's possible we could see rates go lower. Just remember that hasn't happened that often. In fact, it's only happened twice in the last 40 years. So for the rally to continue, traders must be really concerned about the credit markets.

Tuesday, December 4, 2007

Translating "Fedspeak"

I want to go on record as saying I am not a big fan of attempting to divine the Fed's thoughts or policy intentions. Frankly, I think it is pretty much a losing game. In addition, I bought Bernanke's original statements that he wouldn't bail out the financial markets and was pretty much burned in the process. That being said ......

The Federal Reserve has its own language. As a tax lawyer, I am well aware of bizarre language (ever try and work with the tax code?) The Fed is the same way. They have their own way of talking.

There have been a few recent fed speeches that seem to indicate the Fed is deeply concerned about the markets and will most likely lower interest rates at their next meeting.

Let's start with San Francisco Federal Reserve President Janet Yellen:

With these developments in mind, let me review the economic situation. By the time of the October meeting, the data indicated that the economy had turned in a very strong performance in the second and third quarters. However, the fourth quarter is sizing up to show only very meager growth. The current weakness probably reflects some payback for the strength earlier this year—in other words, just some quarter-to-quarter volatility due to business inventories and exports. But it may also reflect some impact of the financial turmoil on economic activity. If so, a more prolonged period of sluggishness in demand seems more likely. The timing of the slowdown certainly matches well with the financial turmoil explanation. Of course, much of the data that drove the third quarter strength cover the earlier part of that quarter, just the very beginnings of the turmoil in July and August, and therefore probably do not reflect its effects very much. However, the data for the end of the quarter—that is, for September—did come in on the soft side, and the data for the beginning of the fourth quarter in October have shown even more of a slowdown.


While correlation does not usually mean causation -- that is, just because things happen at the same time does not mean one causes the other -- her statement that, "The timing of the slowdown certainly matches well with the financial turmoil explanation." makes a great deal of sense. Credit is the life blood of the economy; when its harder to get, everybody suffers.

In addition, recent numbers have not been good. Personal consumption expenditures were weak, as were durable goods. Oil is a drag. Retail sales are fair but not great. In short, the numbers could be a lot better.

I’d like to go into this “story” in more detail. First, the on-going strains in mortgage finance markets seem to have intensified an already steep downturn in housing. Indeed, forward-looking indicators of conditions in housing markets are pointing lower. Housing permits and sales are dropping, and inventories of unsold homes are at very high levels. Moreover, rising foreclosures will likely add to the supply of houses on the market. It’s well known that foreclosures on subprime adjustable rate mortgages have increased sharply over the past couple of years. More recently, we’ve begun to see increases in foreclosures on subprime fixed-rate mortgages and even on prime ARMs. The bottom line is that housing construction will likely be quite weak well into next year before beginning to turn around.

Turning to house prices, many measures at the national level have fallen moderately, and the declines appear to be intensifying. Indeed, the ratio of house prices to rents, which is a kind of price-dividend ratio for housing, remains quite high by historical standards, suggesting that further price declines may be needed to bring housing markets into balance. This perspective is reinforced by futures markets for house prices, which indicate further—and even larger—declines in a number of metropolitan areas this year.


Here Yellen gives a great overview of the basic problems of the housing market. Excess supply = lower prices. Rising foreclosures = more supply for an already bloated market = lower prices.

In addition, with the credit market turmoil listed above, it's harder for people to get loans to buy houses. That means demand is drying up.

In shorter version, here is a chart of the total existing homes available for sale:


And here is a chart of months of inventory available for sale at the current sales pace:


This weakness in house construction and prices is one of the factors that has led me to include a “rough patch” in my forecast for some time. More recently, however, the prospects for housing have actually worsened somewhat, as financial strains have intensified and housing demand appears to have fallen further.


I couldn't have said it better myself. Bottom line: it's getting worse.

Moreover, we face a risk that the problems in the housing market could spill over to personal consumption expenditures in a bigger way than has thus far been evident in the data. This is a significant risk since personal consumption accounts for about 70 percent of real GDP. These spillovers could occur through several channels. For example, with house prices falling, homeowners’ total wealth declines, and that could lead to a pullback in spending. At the same time, the fall in house prices may constrain consumer spending by changing the value of mortgage equity; less equity, for example, reduces the quantity of funds available for credit-constrained consumers to borrow through home equity loans or to withdraw through refinancing. Furthermore, in the new environment of higher rates and tighter terms on mortgages, we may see other negative impacts on consumer spending. The reduced availability of high loan-to-value ratio and piggyback loans may drive some would-be homeowners to pull back on consumption in order to save for a sizable down payment. In addition, credit-constrained consumers with adjustable-rate mortgages seem likely to curtail spending, as interest rates reset at higher levels and they find themselves with less disposable income.

Consumption spending was moderately above trend in the third quarter, and though I had built in some slowing for it in my October forecast, there are signs suggesting even more moderation over the next year or so. For example, although consumers will continue to receive support from gains in employment and personal income, they will also confront constraints because of the declines in the stock market and house prices, the tightening of lending terms at depository institutions, and higher energy prices.


First, note that Yellen admits the importance of mortgage equity withdrawal (MEW) for the current economy. In addition, she also admits the impact of declining wealth on personal consumption behavior which is negative. In short, the housing mess stands a chance of really hitting about 70% of the economy and that's a cause for serious concern.

Here is a chart of personal consumption expenditures from the latest GDP report.
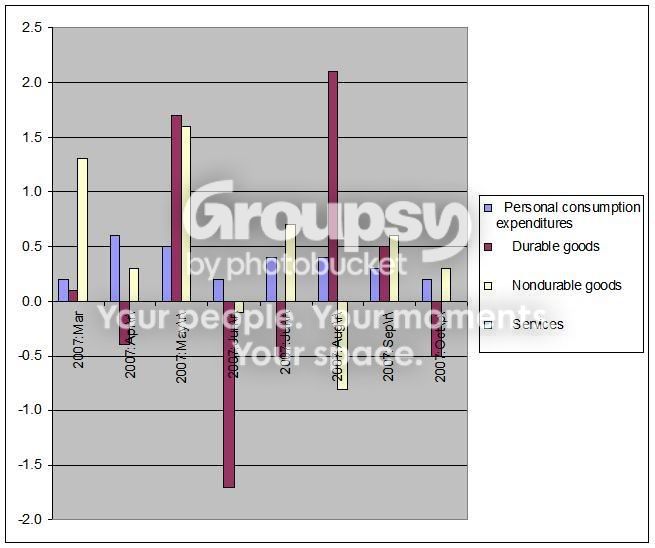


Overall, PCEs were the same from July to August. But they have declined since then. The durable goods number is also cause for concern, as it has jumped around quite a bit.

Moreover, there are significant downside risks to this projection. Recent data on personal consumption expenditures and retail sales are not that encouraging. They have begun to show a significant deceleration—more than was expected—and consumer confidence has plummeted. Reinforcing these concerns, I have begun to hear a pattern of negative comments and stories from my business contacts, including members of our Head Office and Branch Boards of Directors. It is far too early to tell if we are in for a sustained period of sluggish growth in consumption spending, but recent developments do raise this possibility as a serious risk to the forecast.


Short version: Consumer spending is slowing and business leaders are worried. And well they should be.

Next up was Donald Kohn:

Central banks seek to promote financial stability while avoiding the creation of moral hazard. People should bear the consequences of their decisions about lending, borrowing, and managing their portfolios, both when those decisions turn out to be wise and when they turn out to be ill advised. At the same time, however, in my view, when the decisions do go poorly, innocent bystanders should not have to bear the cost.

In general, I think those dual objectives--promoting financial stability and avoiding the creation of moral hazard--are best reconciled by central banks' focusing on the macroeconomic objectives of price stability and maximum employment. Asset prices will eventually find levels consistent with the economy producing at its potential, consumer prices remaining stable, and interest rates reflecting productivity and thrift. Such a strategy would not forestall the correction of asset prices that are out of line with fundamentals or prevent investors from sustaining significant losses. Losses were evident early in this decade in the case of many high-tech stocks, and they are in store for houses purchased at unsustainable prices and for mortgages made on the assumption that house prices would rise indefinitely.

To be sure, lowering interest rates to keep the economy on an even keel when adverse financial market developments occur will reduce the penalty incurred by some people who exercised poor judgment. But these people are still bearing the costs of their decisions and we should not hold the economy hostage to teach a small segment of the population a lesson.


I love this paragraph. While paying lip-service to the idea of moral hazard, Kohn basically says, "the needs of the many out weight the needs of the few" (yes, I was a Trekkie). In other words, ignore what he said in the first paragraph and let the interest rate cuts begin.

Related developments in housing and mortgage markets are a root cause of the financial market turbulence. Expectations of ever-rising house prices along with increasingly lax lending standards, especially on subprime mortgages, created an unsustainable dynamic, which is now reversing. In that reversal, loss and fear of loss on mortgage credit have impaired the availability of new mortgage loans, which in turn has reduced the demand for housing and put downward pressures on house prices, which have further damped desires to lend. We are following this trajectory closely, but key questions for central banks, including the Federal Reserve, are, What is happening to credit for other uses, and how much restraint are financial market developments likely to exert on demands outside the housing sector?

Some broader repricing of risk is not surprising or unwelcome in the wake of unusually thin rewards for risk taking in several types of credit over recent years. And such a repricing in the form of wider spreads and tighter credit standards at banks and other lenders would make some types of credit more expensive and discourage some spending, developments that would require offsetting policy actions, other things being equal. Some restraint on demand from this process was a factor I took into account when I considered the economic outlook and the appropriate policy responses over the past few months.

An important issue now is whether concerns about losses on mortgages and some other instruments are inducing much greater restraint and thus constricting the flow of credit to a broad range of borrowers by more than seemed in train a month or two ago. In general, nonfinancial businesses have been in very good financial condition; outside of variable-rate mortgages, households are meeting their obligations with, to date, only a little increase in delinquency rates, which generally remain at low levels. Consequently, we might expect a moderate adjustment in the availability of credit to these key spending sectors. However, the increased turbulence of recent weeks partly reversed some of the improvement in market functioning over the late part of September and in October. Should the elevated turbulence persist, it would increase the possibility of further tightening in financial conditions for households and businesses. Heightened concerns about larger losses at financial institutions now reflected in various markets have depressed equity prices and could induce more intermediaries to adopt a more defensive posture in granting credit, not only for house purchases, but for other uses a well.


This is a really long-winded paragraph, isn't it?

Here's the short version:

1.) Everybody thought house prices would go up forever.

2.) Because everyone thought house prices would go up forever, lenders got really lax in their lending standards. If you had a pulse, you could get a loan (actually, both of my dogs were recently solicited for a mortgage)

3.) Oooops! Number 1 didn't happen.

4.) That means number 2 was a really bad and stupid idea.

5.) Because of number 2, lenders are not really thrilled about making new loans right now.

6.) In fact, lenders are buttoning down their hatches right now.

7.) In fact, if you want to get a loan, lenders will actually look at things like your credit score and payment history, rather than if you have a pulse.

8.) In fact, even if you have a decent credit score, it's stil going to be harder to get a loan largely because the two largest mortgage purchasers (Fannie Maw and Freddie Mac) are bleeding pretty badly right now.

Central banks have been confronting several issues in the provision of liquidity and bank funding. When the turbulence deepened in early August, demands for liquidity and reserves pushed overnight rates in interbank markets above monetary policy targets. The aggressive provision of reserves by a number of central banks met those demands, and rates returned to targeted levels. In the United States, strong bids by foreign banks in the dollar-funding markets early in the day have complicated our management of this rate. And demands for reserves have been more variable and less flexible in an environment of heightened uncertainty, thereby adding to volatility. In addition, the Federal Reserve is limited in its ability to restrict the actual federal funds rate within a narrow band because we cannot, by law, pay interest on reserves for another four years.

At the same time, the term interbank funding markets have remained unsettled. This is evident in the much wider spread between term funding rates--like libor--and the expected path of the federal funds rate. This is not solely a dollar-funding phenomenon--it is being experienced in euro and sterling markets to different degrees. Many loans are priced off of these term funding rates, and the wider spreads are one development we have factored into our easing actions. Moreover, the behavior of these rates is symptomatic of caution among key marketmakers about taking and funding positions, and this is probably impeding the reestablishment of broader market trading liquidity. Conditions in term markets have deteriorated some in recent weeks. The deterioration partly reflects portfolio adjustments for the publication of year-end balance sheets. Our announcement on Monday of term open market operations was designed to alleviate some of the concerns about year-end pressures.

The underlying causes of the persistence of relatively wide-term funding spreads are not yet clear. Several factors probably have been contributing. One may be potential counterparty risk while the ultimate size and location of credit losses on subprime mortgages and other lending are yet to be determined. Another probably is balance sheet risk or capital risk--that is, caution about retaining greater control over the size of balance sheets and capital ratios given uncertainty about the ultimate demands for bank credit to meet liquidity backstop and other obligations. Favoring overnight or very short-term loans to other depositories and limiting term loans give banks the flexibility to reduce one type of asset if others grow or to reduce the entire size of the balance sheet to maintain capital leverage ratios if losses unexpectedly subtract from capital. Finally, banks may be worried about access to liquidity in turbulent markets. Such a concern would lead to increased demands and reduced supplies of term funding, which would put upward pressure on rates.


Boy, he's a long-winded guy, isn't he?

OK -- here's the short version.

1.) Financial institutions are hording cash right now. Why? Because a lot of them are taking big hits to their capital.

2.) Financial institutions aren't thrilled about lending money to other financial institutions right now. Why? All of those write downs we've been hearing about indicate that a borrower might not be around in 90 days when a short-term loan comes due. This is called "counterparty risk above."

3.) Financial institutions are really concerned about their own capital positions right now. Why? Because chances are they bought some of the sub-prime crap out there and they'll have to write down their assets in the near future. Therefore, they're hoarding cash. This is where the phrase. "the ultimate size and location of credit losses on subprime mortgages and other lending are yet to be determined" comes into play.

4.) The Fed really can't do much about this. Why? It doesn't matter how much cash you have if you don't want to lend it to somebody. But the Fed will try anyway by flooding the market with as many dollars as possible. Hey -- at least it's something, right?

And finally, we have Bernanke's speech:

With respect to household spending, the data received over the past month have been on the soft side. The Committee will have considerable additional information on consumer purchases and sentiment to digest before its next meeting. I expect household income and spending to continue to grow, but the combination of higher gas prices, the weak housing market, tighter credit conditions, and declines in stock prices seem likely to create some headwinds for the consumer in the months ahead.

Core inflation--that is, inflation excluding the relatively more volatile prices of food and energy--has remained moderate. However, the price of crude oil has continued its rise over the past month, a rise that will be reflected in gasoline and heating oil prices and, of course, in the overall inflation rate in the near term. Moreover, increases in food prices and in the prices of some imported goods have the potential to put additional pressures on inflation and inflation expectations. The effectiveness of monetary policy depends critically on maintaining the public’s confidence that inflation will be well controlled. We are accordingly monitoring inflation developments closely.

The incoming data on economic activity and prices will help to shape the Committee’s outlook for the economy; however, the outlook has also been importantly affected over the past month by renewed turbulence in financial markets, which has partially reversed the improvement that occurred in September and October. Investors have focused on continued credit losses and write-downs across a number of financial institutions, prompted in many cases by credit-rating agencies’ downgrades of securities backed by residential mortgages. The fresh wave of investor concern has contributed in recent weeks to a decline in equity values, a widening of risk spreads for many credit products (not only those related to housing), and increased short-term funding pressures. These developments have resulted in a further tightening in financial conditions, which has the potential to impose additional restraint on activity in housing markets and in other credit-sensitive sectors. Needless to say, the Federal Reserve is following the evolution of financial conditions carefully, with particular attention to the question of how strains in financial markets might affect the broader economy.


OK -- here's the translation:

1.) People aren't spending as much because food and gas prices are rising.

2.) The financial markets aren't doing that well and people are noticing. That is adding downward pressure to the markets.

What's really important here is all of the Fed governors have noticed the credit market is in terrible shape. That's the common theme through all of these speeches. And the problems in the credit market were caused by housing -- which isn't going to get better anytime soon. And finally, these problems are starting to negatively impact consumer sentiment and spending.

In short, the Fed is actually paying attention to the economy. The problem is will a rate cut be enough? I've said this over and over again, but the central problem isn't liquidity: it's confidence. When no one has any confidence that a borrower will be around in 90 days, it's difficult to lend money even in the short term. And cutting rates won't do squat about that.

Today's Markets

SPY: -.81%
QQQQ: -.41%
IWM: -1.02%

Finally we have a trend in place. Unfortunately, it's down. Here's a 7 day chart which shows all of the market's action since the big rally.


Notice over the last three days there has been a consistent pattern of lower highs and lower lows. Also note the upper trend line that has provided clear resistance for the SPYs.


Note the same analysis applies to the QQQQs -- which are down 2.6% from their highs at about 52 a few days ago.


And the Russell 2000 is down 3.66% from its high of about 77.8 a few days ago.

Now -- here are some very interesting charts. They are each three days. I have circled all of the gaps down.


Refer back to each corresponding 7 day chart above. We had a strong gap up before the latest three day sell off. That indicates a change in sentiment.

But the serious gaps down indicate a clear hair trigger on the part of traders. Any sign of bad news and they sell.

Let's look at the daily charts.


The SPYs chart shows three down days. Three days ago the SPYs printed a "spinning top":

Spinning Tops are Japanese Candlesticks that have small bodies with upper and lower shadows/wicks that are longer than the body. Spinning tops reflect uncertainty in the market.


Since then the market has sold off. The only good news is the volume has been decreasing on the downside.


The QQQQs have also been declining. However, they found support at the 10 day SMA.


The IWMS have also been declining. But like the SPYs, volume has been decreasing on the downside. And like the QQQQs, the IWMs have found support at their 10 day SMA and the previous resistance line.

These are still very messy markets. While we have a trend in place -- a downside one -- the daily charts don't show any clear trend right now. The large amounts of downside gaps on the daily 5-minute charts indicates traders are extremely nervous and will sell on a dime. In short, the markets are extremely uncertain right now.

More On Housing Related Industries

The post below got me thinking about housing and related industries. Basically, the underlying question is "how are they doing?"

First, here is a graph from the blog Calculated Risk that shows residential and commercial construction spending.


I had to decrease the chart's size to get it on the blog. The red line is residential and the blue line is commercial. The main point I want to get across is commercial construction has helped to pick-up some of the slack caused by the decline in residential construction. As a result, some of the industries below haven't tanked nearly as hard as one would believe given the plight of residential construction.

The charts are from prophet.net, which is a great site for industry graphs. I highly recommend it.

Now -- on to the graphs. All are 5 year graphs, which helps to see the general overall trend of these various sectors.


Lumber had a year long rally that started in July of last year. But the index formed a head and shoulders reversal pattern from the spring to the fall of 2007 and has since fallen through the neckline of the head and shoulders patter.


General Contractors have benefited from the increasing commercial construction; their chart remained strong for the last three years. But it appears the chart has formed a double top, indicating a trend reversal may be occurring. We'll need for the index to drop below the low point between the two tops at roughly 250 to confirm that a double top has formed.


Heavy construction has two uptrends; one that lasts 3.5 years and another that lasts about 4 and a half years. The index has already fallen through the 3.5 year uptrend and found resistance at its previous trend line. That indicates this sector has already experienced a strong sell-off that is related to the current housing market.


General building materials have already broken a 4.5 year uptrend. But we need a stronger confirmation of the trend break to be sure.


Cement has broken a four and a half year uptrend. It formed a head and shoulders reversal formation from early to late 2007 and fell through the neck line in late 2007.

All of these industries have already reversed or are set to reverse. In other words, these sectors look like great shorts right now.

Monday, December 3, 2007

And You Thought Housing Was Already Bad....

From the Street.com

Lennar's (LEN - Cramer's Take - Stockpickr) sale of a chunk of its land portfolio at a steep discount boosts liquidity for the homebuilder, but it also points to troubling signs about the stock's valuation.

The company sold its land to Morgan Stanley (MS - Cramer's Take - Stockpickr) at a 60% discount to book value. That raises the question: What if all of Lennar's land is worth 60% less than what is stated in the company's financials?

If that's the case, Lennar's stock is wildly overpriced.

The Morgan Stanley deal highlights how much land values are plummeting across the country. The discount falls within the range at which builders are shopping deals to real estate vulture funds, sources say.


Yes, you read that right. Lennar sold land on its books for a discount of 60%. Remember -- we're not talking about a product, or a cheap trinket. We're talking about land. Either Lennar was seriously overvaluing its land portfolio or land prices are plummeting.

Yesterday, homebuilders rose:

Investors bid up the value of housing stocks Monday as the U.S. Treasury secretary said a plan to aid strapped homeowners is close to being finished.

Henry Paulson said he is confident there will soon be an agreement to help thousands of homeowners avoid mortgage defaults by temporarily freezing interest rates. Some 2 million subprime mortgages, loans issued to people with spotty credit histories, are scheduled to reset to higher interest rates in 2008.


I have to wonder how long the relief jump will last. Housing is still a complete and total mess.


While the total inventory of new homes has come down:


The months of supply at current sales rates is increasing, indicating demand is really tanking.

And the existing homes market -- which is much larger than the new homes market by a factor of 8.5 -- is experiencing the same problems.


Total inventory of existing homes is high


And the months of supply at current rates of existing homes is still increasing:

Here is a chart of the homebuilders ETF, the XHB.


This is an incredibly bearish chart.

1.) Prices are 34% below the 200 day SMA.

2.) All of the moving averages are headed lower.

3.) The shorter SMAs are below the SMAs.

The only good news in this chart is that prices have jumped over the 10 day SMA over the last two days.


The real estate ETF recently broke a 4-year uptrend. When the ETF tried to rally it ran into resistance at it's previous trend line.

There are a few ways to look at the current chart.


Some traders could see a double bottom. And technically (pun intended and accepted) they would be right. But this is a great example of why technical analysis without fundamental analysis is deeply flawed. As I mentioned above, the fundamental backdrop is terrible, making a rally based on fundamentals highly unlikely. As a result, I think the best way to look at this chart is a sell-off, followed by a rally, followed by a further sell-off.


A look at the moving average picture makes this analysis more likely:


1.) Prices are below the 200 day SMA.

2.) The shorted SMAs are below the longer SMAs.

3.) Prices are below the SMAs.

4.) All the moving averages are heading lower.

However, to confirm this isn't a double bottom, we'll need a price move below the previous lows of about 67 or so.

The Paulsen plan does place a strong wild card into this scenario. Traders are looking for any sign that Washington is doing something about housing. And the plan fills that void. However, the devil is in the details. We'll have to see how that plays out. In addition, it seems the plan would help the financing arm of the mortgage business rather than the builders.

But at the very least, the plan could stop the downward move for awhile while traders figure out if the plan is any good or not.

Today's Markets

SPYs: down .75%
QQQQs: down .74%
IWM: down 1.04%


All of the averages had similar patterns today -- up until a bit before lunch then down for the rest of the day. The SPYs had an end-of-the-day broadening pattern which is a reversal pattern.

Also notice we had two gaps downward today. But also notice the gaps down were not followed by extreme downside action. I think this indicates the Bernanke/Paulsen floor is still in place.


With the QQQQs, we see a much cleaner version of the up and down nature of today's trading. With the QQQQ's notice the gap down two bars before the close on high volume. The market wanted to drop but didn't.


The close came just in time for the Russell 2000. Notice the heavy selling at the end. The index wanted to dive but the close prevented that from happening.

What's important today is none of the markets could continue their respective rallies. The bullish sentiment just wasn't there. But in the context of last week's advances, today's sell-off still looks like a natural, profit taking session.

There are two other charts that I think are important right now.


Although the transports participated in last week's rally, notice they didn't break their overall, six-month downtrend. The index is still below the 200 day SMA by 7% which is not good.


The financials broke their two-month downtrend but are slipping back below that trend. We need a few more days of price action to see if this continues or not. However - it's also possible we're seeing a simple sell-off from last week's action here. Because the financials are the largest sector to the S&P 500 their action is very important.

Overall, the markets still look really messy -- there isn't any disciplined coherent action in any one direction.

Profits Picture is Dimming

From Bloomberg:

U.S. corporate profits are in a recession, and the entire economy may not be far behind.

Slower sales and higher energy and labor costs are forcing companies from Bear Stearns Cos. to Pitney Bowes Inc. to reduce spending and hiring. Their efforts to keep earnings from eroding even further raise the risk that the economy, already weakened by the steepest housing slide since 1991, may shrink sometime next year.

``The earnings recession has already arrived,'' says David Rosenberg, North America economist for Merrill Lynch & Co. in New York. ``We are going to see an economic recession in '08.''

Corporate profits, as measured by the Commerce Department, fell at an annual rate of $19.3 billion in the third quarter from the second, as domestic earnings dropped by $41.2 billion. The drag from sagging U.S. sales and huge writedowns offset robust earnings abroad, fueled by the weak U.S dollar. The fourth quarter may be an even bigger bust.

``In the third quarter, the tide shifted, and for the worse,'' says Joseph Quinlan, chief market strategist for Bank of America Corp. in Charlotte, North Carolina. ``The domestic-profits squeeze is in its early stage


Let's look at a chart from Econoday:


There is some interesting information in this chart.

1.) Notice that in the 1990s, corporate profit growth was more consistent. From 1992-1997, year-over-year percent change came in between 10% and 20% on a steady basis. While there were no high-flying years, there also weren't any low-flying years either.

2.) The huge spike up in early 2003 is more the result of historical placement than accelerating earnings.

3.) The spikes 2004 are partially the result of placement -- that is, comparisons to particularly weak years. However, there are also some incredibly strong data points that are the result of a strong corporate earnings environment.

4.) The year-over-year numbers have been coming down since early 2005.

5.) Note the last three year-over-year comparison numbers aren't really that strong, especially compared to previous quarters. In other words, the earnings growth has been slowing for a bit.

When we compare the last three quarters growth (Q107, Q207 and Q307) with the SPY chart we get some very interesting points. First, here is the SPYs chart.


Note the SPYs dropped hard at the beginning of March. This would roughly correspond to the beginning of announcements for the first quarter (Q107) earnings season.

The SPYs also dropped hard in August. Part of the is the result of the Bear Stearns announcement regarding its two now bankrupt hedge funds. But also consider that this would also correspond roughly to the middle of announcements for second quarter (2Q07) earnings season.

Also note the SPYs peaked in early October and started declining since then. This roughly corresponds to the beginning of third quarter earnings season (3Q07).

While there are other important reasons for the markets' sharp sell-offs this year, the earnings environment cannot be ignored.

Manufacturing Slowing

From CNBC:

Growth in U.S. factory activity slipped in November to the lowest since January as tight credit conditions and the housing downturn restrained production, according to an industry report released Monday.

The Institute for Supply Management said its index of national factory activity edged down for the fifth straight month, to 50.8 from 50.9 in October, above economists' median forecast for a slip to 50.5. A reading of 50 denotes growth.


Here is a link to the report.

Let's coordinate this data with other data points.


Durable Goods orders have been in a general decline for the last two years. But look closely at the blue line which is the year-over-year percent change. Notice it has been in negative territory for most of the time since late last year.


Industrial production has been declining since last last year. However, the overall growth is still positive. It's in a slower growth phase right now.


As a result of all this negatively in the, the industrial ETF has been declining since early October. While is is currently over the 200 day simple moving average(SMA), the shorter SMAs (the 10 and 20) are both headed lower. The 50 day SMA recently turned lower as well. The index has yet to convincingly break the upside resistance from the downtrend line started in early October. Traders are obviously concerned about this sector.

It's also interesting to note that while exports have been increasing strongly for most of this year, that boost has not saved this sector from the market downturn.

Read This Now

Go to this link at Afraid to Trade. He talks about sector rotation, which right now is very revealing.

Sunday, December 2, 2007

The Market Will Make An Ass Out Of You Whenever Possible

One Thursday I wrote the following regrading market direction:

Going Up: I'd assign this at most a 20% possibility. There is just too much bad news out there. Also consider today's GDP announcement and its lack of impact on the markets. If that news had come at the beginning of an economic expansion, the markets would probably have exploded. Instead we got a very lackluster response. I think the markets know that number is yesterday's news and the economy is going into a weaker period. In addition, there is a ton of bad news out there. This week's housing news was terrible and indicated we're nowhere near bottom. And the durable goods number was another bad number.


As I hope I note often, the market will make an ass out of you whenever possible. And the market has a million ways to do that on a regular basis.

In my defense I will note I wrote that before Bernanke's Thursday night speech where he made this comment:

The incoming data on economic activity and prices will help to shape the Committee’s outlook for the economy; however, the outlook has also been importantly affected over the past month by renewed turbulence in financial markets, which has partially reversed the improvement that occurred in September and October. Investors have focused on continued credit losses and write-downs across a number of financial institutions, prompted in many cases by credit-rating agencies’ downgrades of securities backed by residential mortgages. The fresh wave of investor concern has contributed in recent weeks to a decline in equity values, a widening of risk spreads for many credit products (not only those related to housing), and increased short-term funding pressures. These developments have resulted in a further tightening in financial conditions, which has the potential to impose additional restraint on activity in housing markets and in other credit-sensitive sectors. Needless to say, the Federal Reserve is following the evolution of financial conditions carefully, with particular attention to the question of how strains in financial markets might affect the broader economy.


On Friday the markets interpreted these comments as supporting further rate cuts at the next Fed meeting. As a result, the markets gapped higher at the open. In other words, my prediction that the upside potential was 20% wasn't spot on (to say the least).

Let's look at last week's charts to see what happened.


The SPY's formed a double bottom on Tuesday. They gapped higher on Wednesday, consolidated in a triangle pattern on Thursday and gapped higher at the open on Friday. They also closed on Friday with a rally on heavy volume. This indicates traders were willing to hold positions over the weekend. This tells us traders are less concerned about bad news happening over the last few days (which it hasn't in any meaningful way).


The QQQQs consolidated in a triangle pattern on Monday and Tuesday. They gapped higher on Wednesday then hugged a trendline for the rest of the week. Like the SPYs, we see strong buying at close on Friday.


The IWMs (Russell 2000) also had a double bottom on Tuesday. They gapped higher on Wednesday, formed a bull market flag on Thursday and gapped higher at the open on Friday. However, they dropped for most of the day on Friday. However, they had a strong volume showing at the close of trade without much price appreciation.

What can all of these charts tell us?

1.) The markets are really messy right now. While last week's general trend was up, notice it was by fits and spurts rather than a nice gentle move upward.

2.) There were two upward gaps each on the SPYs and IWMs. Gaps mean there was a rapid change in sentiment. In other words, something pretty fundamental changed. That something was the feeling the Fed will cut rates. My guess is traders are no longer thinking 25 basis points but 50. That would support the radical moves we saw last week.

Let's go to the daily charts.


The SPYs broke their downward trend line and gapped up through the 10, 20 and 200 day simple moving average (SMA). That is one hell of a move. The SMAs will now provide support for the market which is good news for the bulls. Also note that volume was pretty good.


The QQQQs moved through the 10 and 20 day SMA last week. They also broke out of a consolidation pattern. They did run into upside resistance from the 20 day SMA on Friday. However, they also had a good move last week on decent volume.


The Russell 2000 broke through resistance and the 10 and 20 day SMA last week. Volume was decent. However, this index is still trading below the 200 day SMA by almost 5%, so things aren't very rosy for this index.

I want to go back to Bernanke's statement for a minute. Remember, most of the time the Central bank gives us standard patter, like "the US economy is operating below potential, but the chance of negative fallout is small." Translation: we're not operating at full potential, but the sky isn't falling either.

Note the Bernake specifically mentions a lot of the major problems in the markets and the economy. That's pretty atypical. He notes declining equity values, increasing credit spreads, increasing writedowns, and increased short-term funding pressures. In short, Ben is basically saying things are really bad right now. As far as he is willing to be in public, it sure sounds like Bernanke is almost scared about what is happening. I could be wrong on that, but for him to come out and express his concern about all of those events is I think very telling.

The bottom line is I think the Fed's statements last week -- and Bernanke's in particular -- placed a floor underneath the market barring any really bad news. Bernanke's statements seem to indicate he is deeply concerned about the economy right now -- and there are plenty of reasons to be concerned. This concern would logically lead to a rate cut in the current economic environment.

UPDATE: Today's IBD makes the same conclusion:

The turnaround on Wall Street last week coincided with two reversals in Washington.

First, Federal Reserve policymakers started talking like doves, making clear that interest-rate cuts are back on the table. Then the Treasury Department picked up its bully club, setting aside its concerns about a heavy-handed approach to aiding subprime borrowers at risk of defaulting on their mortgages.

Fed Chairman Ben Bernanke said Thursday night that the economic outlook has been "importantly affected over the past month by renewed turbulence in financial markets."

While Bernanke said the Fed will be "exceptionally alert and flexible" in responding to incoming data, Treasury Secretary Henry Paulson has seen enough data to conclude that the housing market needs a stronger response from Washington.

Instead of encouraging lenders to provide forbearance to borrowers on a case-by-case basis, Paulson is now pushing the mortgage industry to provide broad-based relief. Treasury hosted a meeting with industry officials and financial regulators on Thursday, and reports said the details of an agreement could be announced by the end of the year.


IBD also highlights the Treasury's ideas for dealing with the mortgage crisis. I haven't formed an opinion about this plan. However, the markets are obviously encouraged that Washington is doing something. As with anything like this, the devil will be in the details.

Mish thinks the plan is doomed.

P and F Chart of the SPYs

Point and Figure charts are a great way to cut out all of the market noise that day-to-day gyrations can create. Here is a P&F chart of the SPYs.


Notice the following.

1.) In the last significant move of 2003, 2004, 2005 and 2006 the SPYs broke through previous resistance levels on strong volume. While not all of the volume moving into the market at this time was up volume, the total volume and the corresponding price action indicates the bulls were in charge of these rallies.

2.) In 2007, the price action indicates increased volatility. For this P&F chart to print a new row prices have to move at least 4 points. In other words, there is a very big battle going on right now between the bulls and the bears that has not been resolved in either's favor.

3.) Notice there is incredibly strong resistance in the 156 and 158 area. In early 2007, the SPYs tried to advance beyond 156 twice and were rebuffed. The SPYs advanced to the 158 area later in the year dand couldn't move beyond. In other words, the upper 150s are an incredibly important area of technical resistance for the average.

4.) Since late August 2007, the SPYs have had a pattern of lower highs and lower lows. The move has been gradual, but it is there.

The price action in 2007 is what concerns me the most, especially when compared with 2005 and 2006. In those two years the market had at most 4 simple price trends. In 2007 we have a jumbled mess. The recent declining action and increased volatility are also a concern.

Now, this isn't a bad chart, but it's not a good chart either. It tells us the market is looking for direction but hasn't found one. It also tells us that traders have more of a hair trigger right now as evidenced by all of the volatility. But prices haven't dropped hard in comparison to previous advances.