Showing posts with label PCEs. Show all posts

Wednesday, March 21, 2012

1955: PCEs


The chart above shows the percentage contributions that PCEs contributed to GDP growth and the contribution of various PCE sub-categories to overall growth.  Notice the large increase in durables in the first two quarters of the year.  This number decreased a bit in the third quarter and went negative in the fourth.  Non-durables contributed in the second and fourth quarters while services picked-up in the third and fourth.

The above chart shows the importance of pent-up consumer demand.  As the US moved into the heart of the 1950s expansions, jobs were plentiful, leading  to more income.  This in turn led to people buying more things.  The table below really shows the growth:


The above chart shows the relationship between disposable personal income and PCEs.  DPI increased strongly in the year, largely thanks to collective bargaining agreements with various unions throughout the year. The low rate of unemployment also helped.  From the Economic Report to the President, 1955:


Notice the durables goods rose a bit, but remained at a lower percentage of total PCEs. This is the natural development of the economy becoming more centered around the home.  As people moved into more and more houses, they wanted more and more non-durable goods (clothes, etc...) and services (repairmen etc..).  This is one of the primary reasons why housing is so important to an economic expansion -- it creates a tremendous number of ancillary benefits.

The Economic Report to the President Explained it thusly:


The above two charts show that consumer credit was an important part of the expansion.  The top chart shows the importance of mortgage credit outstanding, along with the government's promotion of home ownership as a policy goal.  The lower chart shows other consumer credit, and also shows a tremendous amount of growth.


Monday, March 19, 2012

Consumer spending pattern does not support ECRI's recession call

- by New Deal democrat

This week I want to revisit and update my forecast from the beginning of the year. That forecast boiled down to softness in the first half, possibly including one quarter of negative GDP but escaping a recession, and a stronger second half. Since that time I've written a number of posts considering ECRI's recession call, trying to understand their argument while at the same time noting the wealth of contrary data. Since I don't get to write the headline when my blog posts are republished elsewhere, let me be clear about my current thinking as to ECRI's calls. That is:

1. their original call for a recession by the end of 2011 was wrong. Period. Doubters need to go back and listen to the September interview on CNBC where Lakshman Achuthan was very explicit that the recession would start no later than the next quarter, i.e., 4Q 2011.

2. the jury is out on their revised recession call of recession by the end of 2Q 2012 (although the data continues to tilt away from that view).

3. the original explanation for the revised recession call, made in a series of interviews a few weeks ago, was pathetically lame. The updated explanation last week, which seems to be a direct response to my recent post, was more nuanced and explanatory.

It'll take a number of posts to state my forecast more thoroughly, but today let me address one point. The best bearish case rests on a weakened consumer whose wages have not kept up with inflation, who is now being battered by yet another spike in the price of gasoline. This is an extremely reasonable point, and appears to underlay ECRI's position, which is that economies don't "muddle along" at sub-2% growth. If an economy decelerates under 2% YoY growth, a recession soon follows. Sputtering real personal consumption expenditures show that the economy is now slowing down into reversal.

As it happens, there is a very important contrary example to the sub-2% thesis, but I'll get to that in another post. In the meantime, let's look at real PCE's. First of all, here's a graph that appeared on Business Insider as the graph that makes ECRI scream recession:


PCE's certainly are very weakly positive YoY at this point. The graph suggests that nonfarm payrolls will follow on a YoY basis.

The problem is, real retail sales also lead nonfarm payrolls . Take the YoY% change in real retail sales, divide by two, and you usually come pretty close to the YoY% change in nonfarm payrolls about 6 or so months later, as shown for the last 10+ years in this graph:
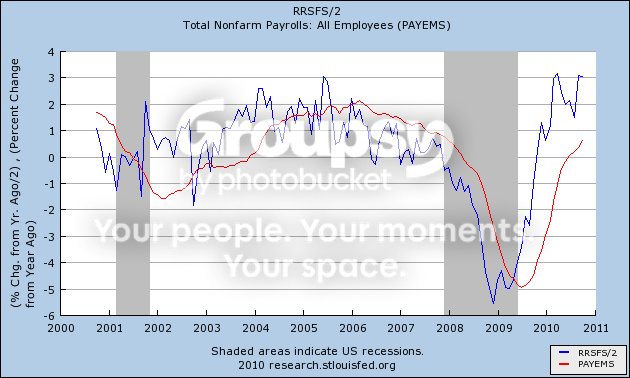


Retail sales constitute about 50% of PCE's. It should be no surprise, then, that the two make peaks and troughs simultaneously:


Note, however, that real retail sales are much more volatile. And, as this graph below (subtracting YoY PCE growth from YoY real retail sales growth through 1997) shows, in a very specific and non-random way:


Note that early in economic expansions, YoY real retail sales growth far outstrips YoY PCE growth. As the economy wanes into contraction, YoY real retail sales grow less and ultimately contract more than YoY PCE's. You can see that by noting that retail sales minus PCE's are always negative BEFORE the economy ever tips into recession. That's 11 of 11 times. Further, in 10 of those 11 times (1957 being the noteworthy exception), the number was not just negative, but was continuing to decline for a significant period before we tipped into recession. This makes perfect sense, as retail sales generally include many far more discretionary purchases. As the economy accelerates, consumers make more discretionary purchases. As it slows, the more discretionary retail purchases are the first things cut.

So what does that relationship show now? Since you know I'm a smarta$$ and I'm saving a surprise for last, here's the graph up through the most recent data:


Not only is the relationship not negative, not only is it stable for the last few months, but it remains at a level of positivity that has only been exceeded four times in the last 60+ years (once in the 1940s, once in the 1950s, and twice in the early 1970s).

Despite the perfectly rational bearish argument cited above, the facts on the ground are that consumers are not cutting back on discretionary purchases to preserve other spending. Until they do, consumer spending does not support any claim that a recession has begun or is even imminent.

Wednesday, February 29, 2012

1954: PCEs


The above chart shows the percentage contribution PCEs made to to GDP for the four quarters of 1954, along with the contribution of various sub-parts of PCEs. Note the incredible strength of PCEs -- consumers are spending a lot of money on an assortment of items.


The above chart is from the Economic Report to the President, 1955.  It simply highlights the incredible growth in a variety of conumer goods that were purchased by consumers during this time.  As the report highlighted:


Also consider the following chart:


 The above chart shows PCEs, income and sales.  Notice that we don't see an increase in disposable personal income until the end of the year.  This is due to the recession which lasted until July 1954.  However, thanks to a well-executed policy to limit the impact of the of the slowdown, the recessions overall effect was mild (from the ERP):


The above chart highlights now consumers continued to purchase a constant amount of durable goods, but expanded their purchases of both services and non-durable goods.

Also helping this process was the consumer finance sector, as noted by the Federal Reserve:


Tuesday, January 31, 2012

1953 PCEs


1953 is a year with two sub-parts.  The first two quarters we see decent growth.  In the first quarter, the growth is pretty even, spread among durable, non-durable and service purchases.  In the second quarter, we see a slight drop in durable good purchases.  In the third quarter, non-durable goods purchases subtracted sharply from growth, while durable goods and lack of service purchases were the reason for the drop in the fourth quarter.


The above chart is fascinating, as it puts PCEs in perspective for the early 1950s expansion.  Overall durable goods purchases remained fairly constant, coming in between $25 and $30 billion.  However, service purchases continued to increase, moving up constantly for the entire expansion.  Non-durables topped-off in 1953 and moved slightly lower in 3Q53 and 4Q53.

The above chart chart places the preceding observation into more detail.  This expansion was about autos and homes, as evidenced by the purchases of autos and furniture.  Also note how housing services continued to rise.  Finally, food purchases saw strong gains, probably because we were still dealing with a culture that was getting away from war rationing. 


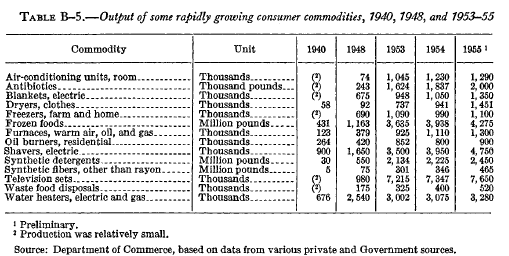
The above chart of various consumer goods outputs really highlights the extent of the growth in consumer spending.  In 1950, we made 3 million TVs.  That number nearly doubled by 1953.  Air conditioner output increased by a factor of 10!  Clothes dryer output doubled. 

This was the consumer on steroids.